Retirement Planner for Two Working Spouses with Different Retirements
Retirement Planner for Two Working Spouses with Different Retirements. When both of you earn a paycheck but stop working in different years, the retirement planner for two working spouses with different retirements shows whether your combined retirement savings can cover the life you want after the last paycheck stops. Enter your incomes, contributions and ages, and you get a projected nest egg, a yearly spending need, and the gap, if any, between them. Pair this with the life expectancy calculator online for a fuller picture before you make a decision.
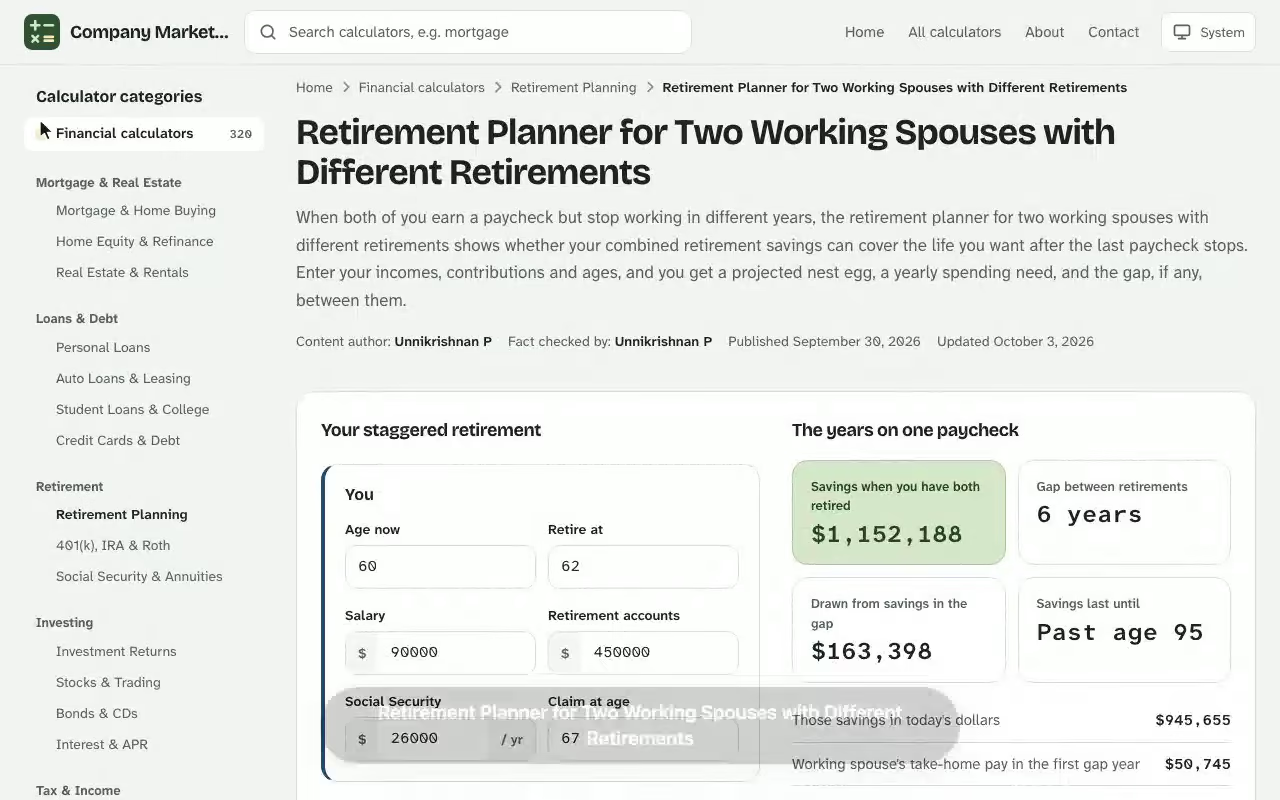
The years on one paycheck
Savings when you have both retired
–
Gap between retirements
–
Drawn from savings in the gap
–
Savings last until
–
Those savings in today's dollars–
Working spouse's take-home pay in the first gap year–
Spending not covered by pay or benefits, first gap year–
Early-withdrawal tax (under 59½)–
Joint savings run out–
–
Drawing order compared
The same plan run both ways. After-tax value counts retirement accounts net of the withdrawal tax rate.
Result
Joint savings first
Retirement accounts first
Year by year
For the drawing order you chose, in future dollars. Withdrawals from retirement accounts include the tax on them.
Your age
Spouse's age
Stage
Take-home pay
Social Security
Spending
From joint savings
From retirement accounts
Total savings at year end
Results are estimates for educational purposes and are not financial, tax or legal advice.
How the Retirement Planner for Two Working Spouses with Different Retirements Works
A retirement planner built for a couple does one job a single-person tool cannot: it adds two incomes, two sets of contributions and two Social Security benefits into one household picture. The planner grows what you have saved today, adds what both of you keep contributing, and then compares the balance at your retirement date with the annual cost of the retirement you describe. Try the retirement nest egg calculator to run your own numbers — everything is calculated in your browser and nothing you enter is stored or sent anywhere.
Household status and why it matters
The first choice is your household status, because it decides whose earnings feed each Social Security estimate. The tool offers four options:
Household status option
What it assumes about income and Social Security
Single
One income, one Social Security benefit, nobody else sharing the household in retirement
Married one spouse working
One paycheck; the working spouse's earnings set a spousal Social Security benefit
Married both spouses working
Two paychecks and two benefits, with a higher spousal amount used only if it beats a spouse's own
Unmarried partners sharing household
Two paychecks, two separate benefits, and no spousal benefit for either person
For most couples reading this page, Married both spouses working is the right setting. Pick it first, because every later input is read in that context.
Annual earned income for you and your partner/spouse
Type your annual earned income as gross pay before taxes, then do the same for your partner/spouse. Count wages and self-employment earnings only. Interest, dividends and rental income belong elsewhere, since Social Security is based on earnings rather than investment income.
Employer and employee retirement contribution percentages
Each of you enters two percentages of salary: the employee retirement contribution you defer from your paycheck and the employer retirement contribution your company adds. These can flow into a 401(k), a 403(b) or any similar workplace account. Two people, two employers and two matching formulas mean the combined rate can differ a lot from either individual rate.
Retirement Planning Inputs: Age, Savings and Growth Assumptions
Good retirement planning depends less on the answer than on the honesty of the assumptions behind it. These are the inputs that move the result most. The free gross distribution calculator is free to use with no sign-up, and works on desktop and mobile.
Your age, partner/spouse age and years until retirement
Enter each current age, then the years until retirement. The planner treats this as the number of years before you start drawing from your savings, so a couple who will not stop together has to decide which date to model. The next section explains how to handle that.
Current retirement savings and monthly contributions
Your current retirement savings is everything already set aside across 401(k) plans, IRA accounts, a Roth IRA and annuities. Any additional monthly retirement contributions outside payroll deferrals go in a separate field; the tool assumes they are made at the start of each month and rise with inflation until you stop working.
Rate of return and the expected inflation rate
Two assumptions carry the most weight. The rate of return is what you expect your investments to earn before taxes, so choose it from your real investment mix rather than a hopeful guess, and a mix of stocks and bonds will land somewhere between the two extremes. For perspective, the S&P 500 has delivered an average annual compounded rate of return near 11 percent since 1970, but that came with volatility a balanced portfolio would soften. Your expected inflation rate is the other lever. The consumer price index is the usual yardstick, and a long-term average near 3 percent is a sensible starting point. The planner applies both figures to each spouse's balance until the retirement date you enter.
Pre-retirement income desired in retirement
Most households need less than 100 percent of their working pay. You choose a percentage of pre-retirement household income, and the planner turns it into a dollar target. Use an after-tax figure if most of your money sits in tax-deferred accounts, since every withdrawal from those accounts is taxable.
Planning When Spouses Retire in Different Years
The title promises a plan for spouses with different retirements, and this is where couples most often go wrong. The calculator reads one retirement date, so you model a staggered exit by running it more than once.
Staggered retirement dates and your retirement plan
Run your retirement plan once for the earlier date and once for the later one. The first run shows the cost of the earlier exit: fewer contribution years, more years of drawing down. The second shows how much the extra work years of the later spouse repair the gap. Comparing the two gives you a range instead of a single hopeful number.
Retirement work income and annual surplus
If one of you plans to keep working part time, enter it as retirement work income; it is adjusted for inflation before and during retirement. Any annual surplus, the amount by which your income streams (pensions, Social Security and other pay) exceed what you need that year, can be reinvested rather than spent. Other misc. income, such as a pension or rent, is not adjusted for inflation, so enter it in today's dollars with that in mind.
Number of years in retirement for the longer-living spouse
Set the number of years in retirement to cover the spouse likely to live longest, not the average of the two. For a couple, the odds that at least one of you reaches the late 80s or 90s are much better than for either alone, and a plan that ends when the first spouse dies understates what your savings must do.
Social Security, Medicare and Tax Planning for Couples
Benefits and taxes are where two paychecks create real opportunity, and real traps.
Social Security claiming age for each spouse
Social Security pays a reduced benefit if you claim before full retirement age, which is 67 for anyone born in 1960 or later, and a larger one if you delay up to age 70. Each of you picks a claiming age, and the household status you chose sets whether a spousal Social Security benefit could exceed a spouse's own. When one of you earned far more, the lower earner may do better taking the spousal amount, which is why the tool compares them automatically.
Key ages each spouse should check before choosing a retirement year.
Medicare and private health insurance before 65
Most people qualify for Medicare at 65. A spouse who retires at 62 faces three years of private health insurance, and that cost belongs in your expenses and in your retirement needs. Couples with one younger spouse sometimes keep the older one working simply to keep employer coverage in place.
Retirement tax: federal income tax on withdrawals
Pre-tax 401(k) and IRA withdrawals are taxed as ordinary income, so a $1,000 distribution never yields $1,000 of spending. Part of your Social Security may also face federal income tax once combined income passes the IRS thresholds, and most states add their own taxes. Pulling money from a tax-deferred account before 59½ also usually brings a 10 percent penalty on top.
Testing the Retirement Planner on a Couple Three Years Apart
Lena is 59 and earns $73,850 as a school administrator; Tomas is 56 and earns $91,220 as a surveyor. They sit down on a Sunday with their latest 401(k) statements, because Lena wants to stop working when she reaches Medicare at 65, while Tomas assumes he will keep going.
They choose Married both spouses working and enter what they have: $398,500 of combined savings, a 12 percent total contribution rate for each of them (employee plus employer), which is $19,808 a year together, a 6.0 percent return, 2.5 percent inflation, 24 years of retirement and a target of 65 percent of pay. Their combined Social Security estimate is $61,200 a year. For years until retirement they type 6, the date Lena stops.
The planner projects $703,450 at that point. The spending target is $107,296 a year, leaving $46,096 to come from savings, which needs about $1,016,684 by then. The result reads as a $313,235 shortfall, large next to the common rule of thumb of saving ten times your final income.
Tomas changes one input: 8 years, so Lena is 67, her full retirement age, and he is 64. The projection climbs to $831,201 against a need of $1,068,154, a shortfall of $236,953. Still short, so they rerun with $1,100 a month of additional contributions. The balance rises by about $130,647 and the gap narrows to roughly $106,300.
That number gives them a concrete next step instead of a vague worry: Tomas asks his employer for the match schedule, and Lena looks at delaying her claim to 67 before they run the retirement plan again.
Worked Example: Retirement Savings Planner Results for a Married Couple
Here is one realistic couple run through the planner, with every number computed from the same formulas the tool uses.
Inputs for this couple
Input
You
Your spouse
Age
54
51
Annual earned income
$88,600
$64,300
Employee contribution
10% of pay
9% of pay
Employer contribution
5% of pay
4% of pay
Together you hold $487,000 of current retirement savings. Your combined contributions come to $21,649 a year, about 14 percent of your $152,900 household income. You assume a 6.5 percent return before retirement, 2.7 percent inflation, 25 years of retirement, and a target of 70 percent of pre-retirement pay, with $52,400 a year of combined Social Security.
See how the Retirement Planner for Two Working Spouses with Different Retirements works: change the inputs and the savings when you have both retired updates instantly. Enter your own numbers in the calculator above.
The formula behind the projected balance
The savings balance at retirement combines growth on what you already have with the future value of your yearly contributions:
$$B = S \times (1 + r)^{n} + C \times \frac{(1 + r)^{n} - 1}{r}$$
Here \(S\) is current savings, \(r\) the annual return, \(n\) the years until retirement and \(C\) your yearly contribution. With \(n = 11\), your existing savings grow to about $973,587 and your contributions add about $332,779, for a projected balance of $1,306,366.
The projected balance builds from current savings, growth and yearly contributions.
Retirement income need versus projected balance
Seventy percent of $152,900 is $107,030 a year; subtract $52,400 of Social Security and your savings must supply $54,630 a year in today's dollars. Funding that for 25 years, with inflation applied, needs about $1,455,251 at retirement. That leaves a shortfall of $148,885.
Retirement date
Projected balance
Balance needed
Surplus or shortfall
In 9 years
$1,112,355
$1,379,739
-$267,384
In 11 years
$1,306,366
$1,455,251
-$148,885
In 13 years
$1,526,418
$1,534,895
-$8,477
Raising your contributions by $600 a month adds roughly $110,675 by the 11-year mark and trims the shortfall to about $38,210. That is the kind of trade a couple can weigh: two more working years for one spouse, or a few hundred dollars a month more.
The shortfall shrinks from $267,384 to $8,477 as retirement moves from 9 to 13 years out.
Using Your Results to Build a Retirement Savings Plan
Closing a shortfall with savings and contributions
A gap does not mean failure, and every investment decision here is adjustable. You can close it by raising contributions, working longer, trimming the target percentage, or delaying Social Security. Change one input at a time and rerun the retirement calculator so you can see which lever helps most. Catch-up contributions after 50 give both of you extra room in a 401(k) or IRA.
When to talk with a financial advisor
A projection is an estimate, and a financial advisor can stress test it against sequence risk, long-term care costs and a plan to sequence withdrawals across taxable, tax-deferred and Roth accounts. Bring the planner's output to that conversation so you start from your numbers rather than a blank page. If you want a second angle, a retirement planner calculator can be rerun each year as pay, balances and returns change; the risk of drifting off course shrinks when you check regularly.
Update your household status after any life change.
Recheck Social Security estimates once a year.
Review your lifestyle and health assumptions every few years.
Retirement Planner for Two Working Spouses with Different Retirements questions
How does a retirement planner work when both spouses have jobs?
It combines both incomes, both sets of employee and employer contributions and both Social Security benefits into one household projection, then compares the savings you will have at retirement with what your target income requires.
What if my spouse and I plan to retire in different years?
The calculator uses one retirement date, so run it twice: once for the earlier date and once for the later one. Comparing the two results shows how much each extra working year narrows or closes the gap.
What household status should two working spouses choose?
Choose Married, both spouses working outside the home. Each spouse then gets their own Social Security benefit, and a spousal benefit is used only if it is higher than their own.
How much of my pre-retirement income will I need?
Many households plan for 70 to 80 percent of their pre-retirement income, but the calculator accepts anything from 40 to 160 percent. Use an after-tax figure if most of your savings are in tax-deferred accounts.
What rate of return and inflation rate should I use?
Pick a rate of return that matches how your savings are invested, since stocks carry higher expected returns and higher volatility than bonds or savings accounts. For inflation, a long-term average near 3 percent, based on the Consumer Price Index, is a common starting point.
Does the planner include Social Security?
Yes. Tick Include Social Security, set the percentage of your estimated benefit to count and choose the age each spouse begins claiming, between 62 and 70. Benefits are reduced before full retirement age and increase if you delay.
How many years of retirement should I plan for?
Plan for the longer-living spouse rather than the average. For a couple, one of you has a good chance of living into the late 80s or 90s, so a longer horizon is the safer choice.