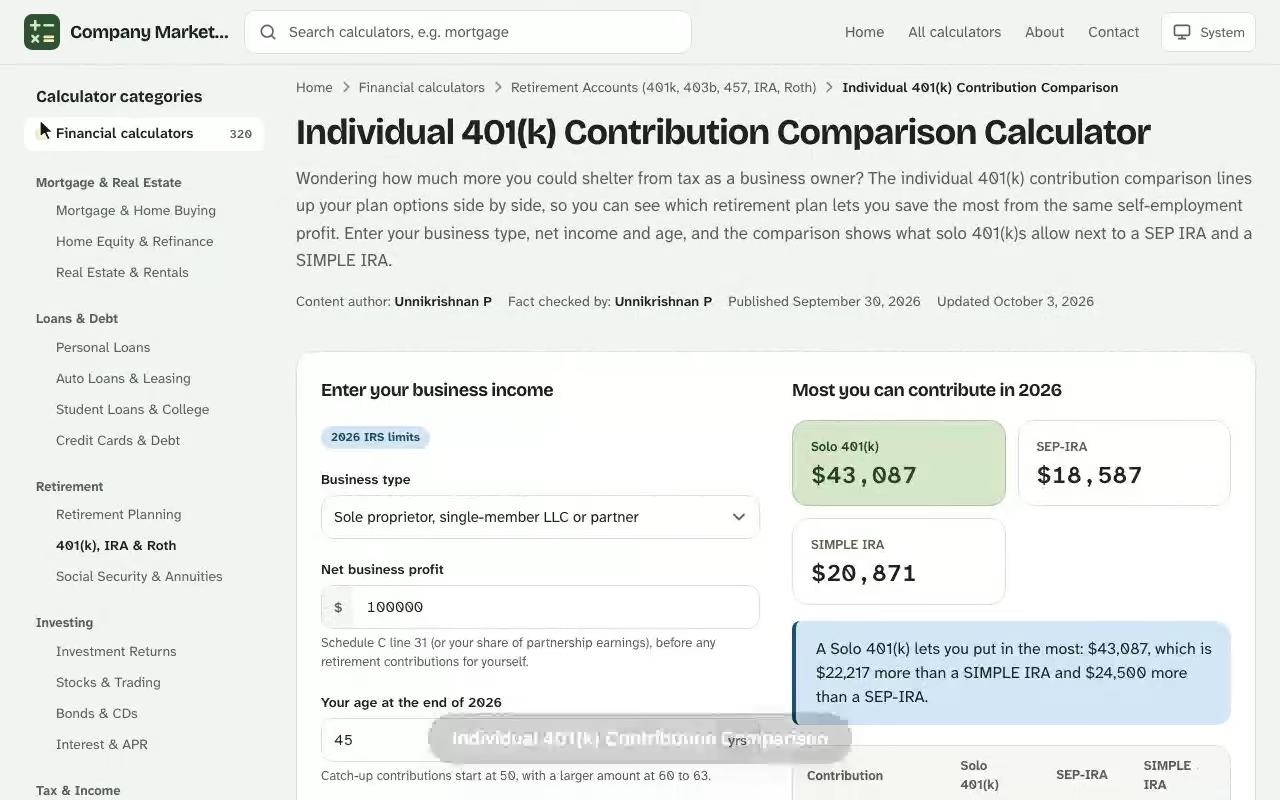
Individual 401(k) Contribution Comparison. Wondering how much more you could shelter from tax as a business owner? The individual 401(k) contribution comparison lines up your plan options side by side, so you can see which retirement plan lets you save the most from the same self-employment profit. Enter your business type, net income and age, and the comparison shows what solo 401(k)s allow next to a SEP IRA and a SIMPLE IRA. Pair this with the free 401k calculator for a fuller picture before you make a decision.
Most you can contribute in 2026
Solo 401(k)
–
SEP-IRA
–
SIMPLE IRA
–
Contribution
Solo 401(k)
SEP-IRA
SIMPLE IRA
Employee deferral
–
None
–
Catch-up
–
None
–
Employer contribution
–
–
–
Total
–
–
–
How the solo 401(k) maximum is worked out
The steps of the IRS Publication 560 deduction worksheet for the self-employed, with 2026 limits and a 25% plan rate.
Net business profit–
Less the deductible half of self-employment tax–
Net earnings from self-employment–
20% of net earnings (25% plan rate ÷ 1.25)–
Employee deferral–
Employer contribution (smallest of 20% of net earnings, $72,000 less deferral, half of what is left after the deferral)–
Catch-up–
Maximum solo 401(k) contribution–
Maximum contributions at other income levels
Same business type, age and options as above.
Net profit
Solo 401(k)
SEP-IRA
SIMPLE IRA
Results are estimates for educational purposes and are not financial, tax or legal advice.
Individual 401(k) Contribution Comparison: What the Results Show
A single set of inputs produces three separate answers, because each plan type measures your income and caps your savings differently. The calculator returns an adjusted earned income figure, the employer contribution, the elective deferral amount, any catchup amount and the maximum contribution allowed for each plan. Reading those five lines across the three columns tells you quickly whether the extra paperwork of a solo plan is worth it for your situation. The tax sheltered annuity tsa calculator is free to use with no sign-up, and works on desktop and mobile.
Inputs: Business Type, Net Income and Current Age
Only three inputs drive the whole result, which is why this contribution calculator is quick to use:
Business type: choose a sole proprietorship or a corporation. The formula differs slightly for each, as explained below.
Net income: for a sole proprietor this is the profit from your tax Schedule C. For a single-owner corporation with no employees other than yourself or your spouse, it is your W-2 wages.
Current age: anyone who reaches age 50 by the end of the year qualifies for extra catch-up contributions, and the allowance rises again for ages 60 through 63.
How to Read the Solo 401(k) Contributions Calculator Output
Start with the bottom row. The maximum contribution allowed is the number to compare, but the rows above it explain where it comes from. A large elective deferral with a small employer contribution means your plan limit is driven by the fixed dollar cap, while a large employer contribution means your profit is doing the work. Using the solo 401(k) contributions calculator this way shows you which lever, earning more or deferring more, actually changes your total.
Solo 401(k) Contribution Limits for the Self-Employed
The Internal Revenue Service sets annual caps, and for 2026 the overall limit for a one-participant plan is $72,000 before catch-up contributions. Because a solo 401(k) lets you wear two hats, you contribute once as the employee and once as the employer. The two pieces are tracked separately, and each has its own ceiling inside the overall limit. The free 401k save the max calculator is free to use with no sign-up, and works on desktop and mobile.
Elective Deferral vs Employer Contribution
The elective deferral is the portion you choose to defer from your own pay. For 2026 the annual deferral limit is $24,500, and it can never exceed 100% of your compensation. The nonelective contributions you make as the employer are capped at 25% of compensation for a corporation, and a self-employed owner uses an effectively lower rate of 20% of net earnings, because the calculation is circular (the contribution reduces the very income it is based on). Together the two pieces cannot exceed the overall limit of $72,000.
Catch-Up Contributions by Age
Once you reach 50, the plan allows an additional $8,000 of catch-up contributions in 2026, which raises your employee limit to $32,500 and your overall ceiling to $80,000. Savers aged 60 to 63 get a higher catch-up of $11,250, which brings the ceiling to $83,250. Catch-up money applies to the employee side only, so it does not depend on how much profit your business earns.
Under 50: no catch-up contributions, deferral limit of $24,500.
Ages 50 to 59 and 64 or older: $8,000 catch-up, ceiling of $80,000.
Ages 60 to 63: $11,250 catch-up, ceiling of $83,250.
The maximum solo 401(k) contribution at four ages on the same $118,600 profit, showing where catch-up contributions start and change.
How a Self-Employed 401(k) Calculates Your Maximum Contribution
The self-employed 401(k), also called a solo-k or uni-k, uses an earned income definition that trips up many first-time filers. The IRS requires a special computation for the owner: compensation means net earnings from self-employment after you subtract one-half of your self-employment tax and the contributions you make for yourself. You can confirm the rate table and worksheets in IRS Publication 560, which is the reference for the deduction.
Sole Proprietor Formula
A sole proprietor first finds the self-employment tax, then the net self-employment income that remains after deducting half of it:
The maximum total is then the employer contribution plus your elective deferral, and the sum is limited to $72,000 plus any catch-up. Use this version if you file a Schedule C or operate as a single-member LLC.
How net profit becomes adjusted earned income once half of the self-employment tax and the employer contribution are taken out.
Corporation and S-Corp Owner Formula
If you run a corporation, the calculation is simpler because the plan is based on W-2 wages paid to you rather than on business profit. The employer contribution is 25% of those wages, and you add your elective deferral on top:
A common mistake for an S-corp owner is to enter distributions or total profit. Only the salary reported on your W-2 counts toward compensation, so a small salary keeps the contribution small even when the business is profitable.
Worked Example: Solo 401(k) vs SEP IRA vs SIMPLE IRA
Suppose you are 44 years old, run a consulting practice as a sole proprietorship and report a Schedule C net profit of $118,600. Your self-employment tax is $16,757.65, and half of that, $8,378.82, is deductible, which leaves net earnings of $110,221.18. The comparison then gives you these figures:
Item
Individual 401(k)
SEP IRA
SIMPLE IRA
Adjusted earned income
$88,176.94
$88,176.94
$106,914.54
Employer contribution
$22,044.24
$22,044.24
$3,306.64 (3% match)
Elective deferral amount
$24,500.00
$0.00
$17,000.00
Catchup amount
$0.00
$0.00
$0.00
Maximum contribution allowed
$46,544.24
$22,044.24
$20,306.64
The solo plan allows more than double what either alternative does, because a SEP IRA accepts only employer money and a SIMPLE IRA has a much lower deferral limit. The SIMPLE column uses the 2026 employee limit of $17,000 and a 3% match; confirm current SIMPLE figures with the IRS before you rely on them.
Maximum 2026 contribution by plan for a sole proprietor with $118,600 of net profit, split into employee deferral and employer contribution.
What Changes With Age
Run the same profit at different ages and only the catch-up row moves. At 52 your total rises to $54,544.24, and at 61 it reaches $57,794.24. The SEP IRA stays at $22,044.24 at every age because it has no catch-up feature, while the SIMPLE IRA adds a smaller catch-up of its own.
Checking Solo 401(k) Contribution Limits for a Freelance Editor
It is mid-October, and Marisol, a 56-year-old freelance video editor, has just closed her books for the third quarter. Her projected Schedule C profit for the year is $164,830 after expenses, and she has already moved $15,200 into a savings account earmarked for retirement. Before she funds anything, she wants to know whether a SEP IRA, which she opened years ago, is leaving money on the table.
See how the Individual 401(k) Contribution Comparison works: change the inputs and the solo 401(k) updates instantly. Enter your own numbers in the calculator above.
She selects sole proprietorship as the business type, types 164830 as net income and 56 as current age, then reads the three columns:
Individual 401(k): $63,137.03, made up of $24,500 deferral, $8,000 catch-up and a $30,637.03 employer contribution.
SEP IRA: $30,637.03, employer money only.
SIMPLE IRA: $25,595.55, including a $4,000 catch-up and a 3% match of $4,595.55.
The gap is $32,500, which is exactly the employee deferral plus catch-up that her SEP IRA cannot accept. Her total sits below the $80,000 ceiling the IRS sets for savers aged 50 to 59, so profit, not the cap, is what limits her; the 20% employer rate on $153,185.13 of net earnings is doing the work.
Her next step is specific. She schedules a $32,500 employee deferral before December 31, using her $15,200 savings plus $17,300 from the next two invoices, and leaves the $30,637.03 employer contribution until her accountant finalizes the return. To test a slow quarter, she reruns the comparison with $150,000 of profit: the employer contribution falls to $27,880.57, so she decides to treat anything above that as a bonus, not a commitment.
Roth and Pre-Tax Options Inside a One-Participant 401(k)
Another advantage of the individual 401(k) plan is that your employee side can be pre-tax or Roth. With pre-tax money you take a tax deduction now and pay income tax on withdrawals later, while Roth contributions are taxed today and grow tax-free. Many plans allow a split, so you can lower taxable income this year and still build a tax-free bucket for later.
A traditional election lowers this year's income tax and suits owners in a high bracket.
A Roth election suits owners who expect higher rates in retirement.
A SEP IRA and a SIMPLE IRA generally do not offer the same flexibility, which narrows your choices.
Solo 401k Eligibility, Fees and Providers
Your headcount decides whether the solo column of the comparison applies to you at all, so check it before you trust the numbers. A solo 401k is meant for a business owner with no common-law employees other than a spouse, so eligibility comes down to your headcount. Freelancers, consultants and other small business owners usually qualify; part-time workers under 1,000 hours a year typically do not count against you. A plan can also be paired with a retirement plan at another employer, but the elective deferral limit applies per person across all of them.
Choosing Among Providers and Comparing Fees
The best providers differ on fees, investment choices, customer service and features such as loans. Some charge a flat annual fee and others charge a percentage of assets, so a larger balance may favor a flat fee. A solo plan can also allow a hardship loan or a borrowing feature, which many IRAs lack, though loans have their own repayment rules. A SIMPLE IRA has a mandatory match and is open to businesses with 100 or fewer employees, which is a different trade-off. None of these fees change the maximum the comparison returns; they only change what you keep after costs.
S-Corp Owner Example: How W-2 Wages Change the Maximum Contribution
The same comparison behaves differently when your business is a corporation. Imagine you are 38, own an S-corp that has no employees, and pay yourself $96,000 in W-2 wages. Your employer contribution is 25% of that salary, or $24,000, and your elective deferral is the full $24,500, so the maximum contribution allowed is $48,500. That is slightly above the sole proprietor in the previous example even though the wage figure is lower than the Schedule C profit, because the corporation formula skips the self-employment tax step and applies the higher 25% rate.
The trade-off is that corporate owners control the number themselves. Raise the salary and the contribution room grows, but payroll tax grows with it. That is why many owners enter several wage levels into the calculator and compare the maximum annual contributions before they set their salary for the year.
Which Plan Fits Your Business? A Quick Decision Guide
The numbers above favor a solo plan for almost anyone who earns a steady profit, but the right choice depends on more than the highest total. Use the questions below to narrow the comparison:
Do you have employees? If you plan to hire full-time staff soon, a SEP IRA or SIMPLE IRA works with employees, and a solo plan would have to convert to a traditional plan.
How much cash can you set aside? If you can only afford a small amount, a SEP IRA's 25% of compensation rule scales down with your profit, while a solo plan lets you defer a fixed dollar amount even when profit is modest.
Do you want a Roth option? Only the individual 401(k) plan in this comparison gives you Roth elective deferrals and loans in the same account.
How much paperwork can you handle? A SEP IRA is the simplest to open; a solo plan adds an annual report once assets pass $250,000.
When a SEP IRA or SIMPLE IRA Still Makes Sense
A SEP IRA can be the better tool if you hire employees, because you must then contribute the same percentage for them, and it avoids a separate plan document. A SIMPLE IRA suits a small team that wants employees to defer their own pay with a required match. Neither beats the solo plan for a one-person business on the raw limit, but each can win on administration.
Common Mistakes When You Compare Individual 401(k) Plan Contributions
Most errors come from entering the wrong income or forgetting the interaction between plans. Watch for these:
Entering gross revenue instead of net income. The formula starts from profit after business expenses, so revenue overstates your limit.
Ignoring the self-employment tax deduction. Skipping the half-deduction inflates your earned income and your employer contribution.
Forgetting other employers. The $24,500 elective deferral limit is per person, so a 401(k) at a day job counts against it.
Treating catch-up contributions as part of the 25% rule. Catch-up amounts sit on top of the employee side and are not based on income.
Mixing business types. A corporation uses W-2 wages, not profit, so selecting the wrong business type changes the answer substantially.
Deadlines and Setting Up the Plan
The timing matters as much as the amount. In general, the plan must be established by the end of the year for the employee deferral to count, while the employer contribution can be made up to your tax filing deadline, including extensions. Keep good records of every deposit so that your annual report and your deduction match what you actually contributed.
Funding Your Solo-K Across the Year
Knowing the annual contribution limit from the comparison is only half the job; the other half is deciding how to spread the amounts it returns across the year without straining cash flow. Solo 401(k)s reward owners who plan the two halves separately. Your employee contribution can be made on a schedule that follows your income, so a freelancer with uneven months can defer a fixed percentage of each client payment and let the total adjust itself. The employer contributions, by contrast, depend on the full-year profit, so most owners wait until the books are closed before deciding how much to add.
Open the plan early in the year so every payment can flow into it.
Defer enough during the year to capture the full elective deferral if cash allows.
Use the year-end profit figure to set the employer contribution.
Rerun the comparison after any large invoice or expense, since net income moves the answer.
Treat the maximum the calculator returns as a ceiling for your retirement plan, not a target you must hit. Fees and investment choices inside the plan change how fast the balance grows, but they never change the limit itself, so rerun the comparison whenever your profit shifts and adjust the remaining deferral to match the new limit.
One-Participant K Rules: Testing, Filing and Withdrawals
The one-participant k is not a different type of plan; it is a traditional 401(k) covering an owner with no employees (and possibly a spouse). Because nobody else participates, you skip nondiscrimination testing, but the advantage disappears if you hire eligible staff. Once plan assets reach $250,000 at year-end, you generally file Form 5500-EZ each year.
Keep the retirement savings goal in mind as well: withdrawals before age 59½ are usually subject to a penalty on top of income tax, and the savings inside a Roth account follow separate rules. Because the rules are specific, you may want to consult a tax professional or your plan provider before locking in a contribution amount.
What is an individual 401(k) contribution comparison?
It lines up the most you can contribute to an individual (solo) 401(k) against a SEP IRA and a SIMPLE IRA using the same business type, net income and age, so you can see which plan lets you save the most.
How does business type change my contribution limit?
A sole proprietor or single-member LLC bases contributions on net self-employment earnings after half of the self-employment tax, with an effective 20% employer rate. A corporation owner uses W-2 wages and a 25% employer rate.
What counts as net income for the calculator?
For a sole proprietor, use the net profit from Schedule C. For a single-owner corporation with no employees other than you or your spouse, use your W-2 wages.
How much can I contribute to a solo 401(k) in 2026?
You can defer up to $24,500 as the employee and add an employer contribution, with the combined total capped at $72,000. Savers 50 and older can add catch-up contributions on top.
What are catch-up contributions and who qualifies?
Anyone who reaches age 50 by year-end can add $8,000 to a solo 401(k) in 2026, and savers aged 60 to 63 can add $11,250. SIMPLE IRAs have smaller catch-up amounts, and a SEP IRA has none.
Why is my SEP IRA limit lower than my solo 401(k) limit?
A SEP IRA accepts only employer contributions, while a solo 401(k) also lets you make an employee deferral, so the solo plan usually allows far more at the same income.
Can I hire employees and keep a solo 401(k)?
A solo 401(k) is meant for an owner with no full-time employees other than a spouse. Once you hire eligible staff, the plan becomes a traditional 401(k) with testing, while a SEP or SIMPLE IRA can work with employees.
Are the results official tax advice?
No. The numbers are estimates based on 2026 limits; confirm your figures with a tax professional or IRS Publication 560 before you contribute.