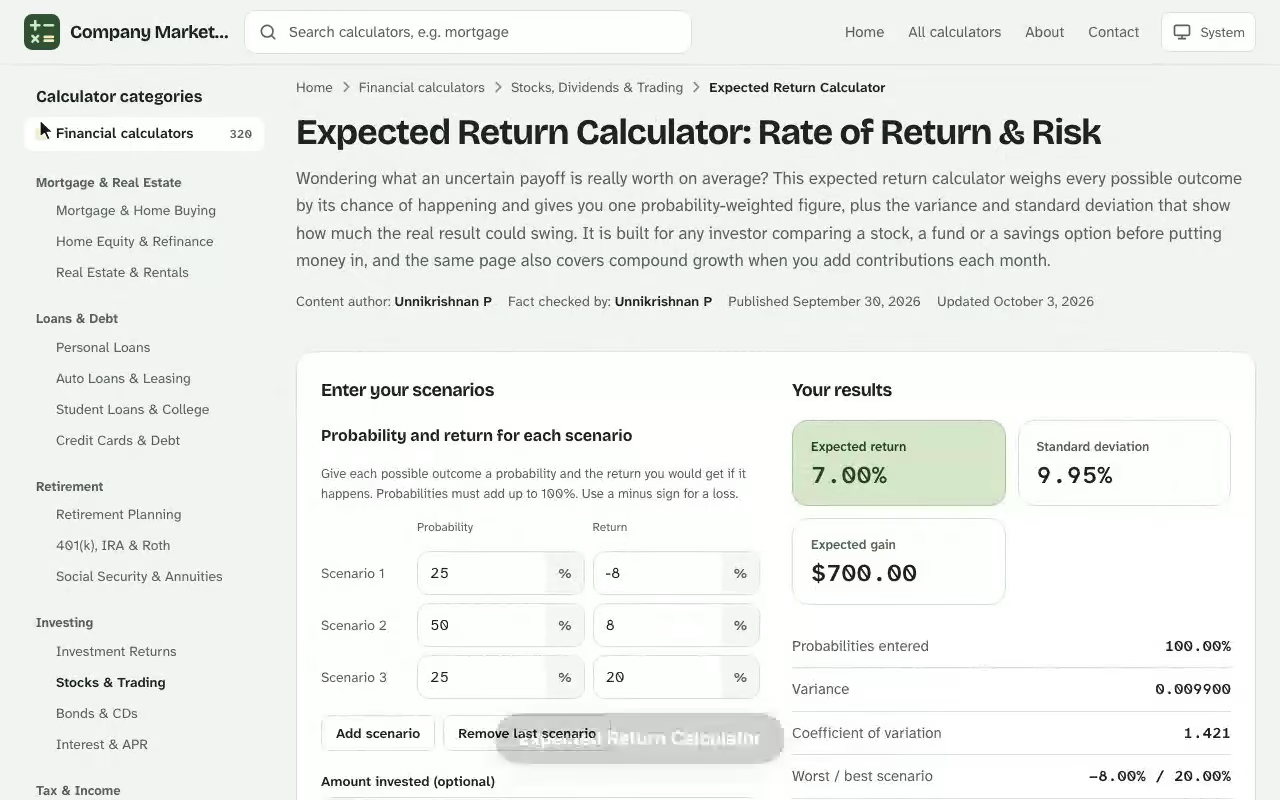
Expected Return Calculator. Wondering what an uncertain payoff is really worth on average? This expected return calculator weighs every possible outcome by its chance of happening and gives you one probability-weighted figure, plus the variance and standard deviation that show how much the real result could swing. It is built for any investor comparing a stock, a fund or a savings option before putting money in, and the same page also covers compound growth when you add contributions each month. Pair this with the free pivot point calculator for a fuller picture before you make a decision.
Your results
Expected return
–
Standard deviation
–
Expected gain
–
Probabilities entered–
Variance–
Coefficient of variation–
Worst / best scenario–
Expected ending value–
Chance of a loss–
The expected return is a probability-weighted average of the scenarios, not a forecast of what will happen; the actual return will be one of the scenarios. Standard deviation measures how far the outcomes spread around that average.
Scenario breakdown
How much each scenario adds to the expected return and to the variance.
Scenario
Probability
Return
Weighted return
Deviation from expected
Weighted squared deviation
Results are estimates for educational purposes and are not financial, tax or legal advice.
How the Expected Return Calculator Works
The tool answers one question: if the same investment were repeated across many possible futures, what average return would you collect? Instead of guessing a single number, you describe the economy in a few states, give each a probability, and attach a return to it. The calculator multiplies, adds and reports the result in seconds, so you can compare two assets on equal terms before you commit any money. The dividend reinvestment breakeven calculator uses the same plain-English approach, so you can compare results side by side.
Inputs you enter
Each row of the form is one state of the economy. For every state you supply two numbers, and the calculator needs nothing else to work out a probability distribution of outcomes:
Probability – how likely that state is, as a percentage. The sum of probabilities must equal 100%, because something has to happen.
Return – the gain or negative return you expect from the asset in that state, for example a stock A or stock B scenario.
States – a recession, a normal economy, a boom, or any other scenario you want to model.
What you get back
After you press Calculate you receive three results: the expected value of the return, the variance, and the standard deviation. The first tells you the payoff you should anticipate; the other two describe risk, meaning how far outcomes can scatter around that average. Read them together, because a high return with a very wide spread is a different proposition from the same return with a narrow one.
Expected Rate of Return Formula
The expected rate of return is the mean of the distribution of future returns. Add up each state's return multiplied by its probability, which is a simple summation: The company stock distribution analysis calculator online uses the same plain-English approach, so you can compare results side by side.
Here \(p_i\) is the probability of state \(i\), \(r_i\) is the return in that state, and \(n\) is the number of states. The result is a mean return measured as a percentage, which makes assets of different sizes easy to compare. It is a forecast built from your own assumptions, so treat it as a planning aid rather than a promise.
Variance and standard deviation
Risk is measured by how far each outcome sits from the mean. Weight each squared gap by its probability to get the variance, then take the square root to get the standard deviation, which is back in the same percentage units as the return itself:
A larger deviation means a wider range of outcomes and a higher risk of landing far from the average. Analysts who go on to price assets with the CAPM start from this same expected return and spread.
Worked Example: Comparing Stock A and Stock B
Take four states of the economy with probabilities that add to 100%. Stock A is a cyclical share; stock B is a steady dividend payer. The table lists the return each one delivers in each state.
State
Probability
Stock A return
Stock B return
Recession
25%
-12%
2%
Slow growth
30%
3%
4%
Normal economy
30%
9%
6%
Boom
15%
24%
8%
For stock A the calculation is \(0.25(-0.12) + 0.30(0.03) + 0.30(0.09) + 0.15(0.24) = 0.042\), so its expected return is 4.20%. For stock B it is \(0.25(0.02) + 0.30(0.04) + 0.30(0.06) + 0.15(0.08) = 0.047\), or 4.70%.
Measure
Stock A
Stock B
Expected return
4.20%
4.70%
Variance
0.013176
0.000411
Standard deviation
11.48%
2.03%
Reading the risk side of the result
Stock B wins on both counts: a higher average and a far smaller spread. Stock A would only come out ahead if you believed a boom was much likelier than the 15% assumed here. This is why the variance and deviation matter as much as the headline number, and why a strong-looking average can hide the potential loss of principal in a recession state.
Stock A and stock B returns in each state, with their probability-weighted expected returns and standard deviations.
Investment Calculator Mode: Compound Growth With Contributions
The same page works as an investment calculator when you already assume a fixed return and want to see the balance a plan reaches. Behaving like an investment growth calculator, it takes your initial investment, an annual rate, the investment length in years and any recurring investments, then projects the final balance.
Imagine a starting amount of $18,500, a periodic deposit of $350 each month, a 7.2% yearly assumption and a 15-year horizon with monthly compounding. The balance after 15 years comes to $167,187. Your total contributions are $81,500, so the interest earned is $85,687, more than you paid in.
Year
Total contributions
Balance
1
$22,700
$24,218
3
$31,100
$36,963
5
$39,500
$51,676
10
$60,500
$99,176
15
$81,500
$167,187
See how the Expected Return Calculator works: change the inputs and the expected return updates instantly. Enter your own numbers in the calculator above.
This yearly view is a compact accumulation schedule; each row shows how the balance builds on the previous one.
How contributions and interest earned build the $167,187 balance over 15 years.
Compound interest and compound frequency
Compound interest pays interest on earlier interest, so compounding is why the balance curves upward instead of rising in a straight line. The compound frequency sets how often interest is added: daily, monthly or yearly. Money that is reinvested this way is compounded more often and grows slightly faster. By contrast, simple interest only ever pays on the original deposit. Each month the future value follows:
where \(B_t\) is the balance after month \(t\), \(r\) is the yearly rate and \(C\) is your monthly annual investment split into twelve equal deposits.
Rate of Return Calculator for Past Performance
Looking backward is a different job. A rate of return calculator takes what you paid, what you ended with, and the time held, then reports the annualized return. Suppose you bought shares for an initial value of $24,800 and sold six years later for a final amount of $31,250. The simple return on investment is:
Spread over six years, the annual rate of return is \((31{,}250 / 24{,}800)^{1/6} - 1 = 3.93\%\). The calculation is a net gain as a percentage of what you put in, a figure sometimes called the holding period return and equal to the return per dollar invested.
Choosing between the two rate of return methods
Use the simple rate of return when you only care how much an investment made in total. Use the annual version when you compare it with another holding that ran for a different number of years, because only a yearly rate of return puts them on the same footing. In both cases the end amount is what you actually received, and the initial investment is what you originally paid, including any initial investment top-ups you made on day one. A strong rate of return over two years says little about long-term skill, so compare like with like.
When regular deposits or withdrawals are mixed in, the cash flow pattern has no neat closed form. Tools then rely on the Newton method, an iteration that refines a guess until the return rate reproduces the final balance. Sometimes the investor's gain is the issuer's price: for equity, the same figure is the cost of equity, built from dividends and capital gains.
What Is a Good Annual Return on Investment?
A fair annual return depends on what you hold. As a rough guide to a historical average, the S&P 500 has returned about 10% a year over the very long run before inflation, while bonds have paid less and stocks in general have swung more. Lower-volatility homes for cash, such as high-yield savings accounts and CDs, pay a modest, predictable investment return with almost no volatility.
Stocks: higher average, larger swings.
Bonds: steadier income, lower average.
Savings and CDs: the safest savings tools, with the smallest growth.
The honest approach is a conservative estimate for planning: run the numbers with a few different rates, then trim the optimistic ones. Any such projection is hypothetical, and a return on stock is not a guarantee, so past results should never be read as a promise of future performance.
Inflation, taxes and real return
The headline rate is not what you keep. Inflation erodes purchasing power, and the consumer price index is the usual gauge. The gap between real and nominal returns is real: with an expected inflation rate of 2.8%, a nominal 7.2% becomes \((1.072 / 1.028) - 1 = 4.28\%\) in today's money. Subtract the tax rate on gains too, and the after-tax result shrinks again, so check fees as well.
Why Expected Returns Differ From Realised Returns
Forward-looking expected returns are averages across possible futures, while a realised rate of return is the single path that actually happened. Over one year, the two can be far apart; over decades, the realised investment return tends to drift toward the average. That is why investing for the long haul and checking your assumptions each year works better than reacting to one result. When you compare investment choices, set each one's expected rate of return next to its spread, and remember that the returns from a volatile asset arrive unevenly, so the investment horizon you choose matters as much as the rate itself.
Managing Risk Behind Your Average Return
Diversification is how you act on the standard deviation the calculator reports. Enter each holding's states into the tool and the spread of a mixed portfolio comes out lower than the spread of its most volatile asset, because bad states rarely hit every holding at once, while the portfolio's average is simply the weighted average of each holding's average. A deliberate asset allocation across equity, debt and cash is therefore an input you can test, and a financial advisor can review the mix with you. Building it is the heart of an investment plan, since the average only matters if you can stay invested through a downturn. Every market exposure adds a state where a loss is possible, so model it before you hold it.
Pricing an Investment Return Against a CD, Step by Step
Priya Raman has $23,640 from a bonus and two choices: a one-year CD paying 4.35%, or a dividend ETF. She treats the ETF as a return on investment question and opens the expected return calculator to model three states of the market. She enters a recession at 20% probability with a -9.4% return, a normal year at 55% with 7.3%, and a boom at 25% with 13.8%. The sum of probabilities reads 100%, so she presses Calculate.
The result is a 5.585% expected return and a standard deviation of 7.96%. Against the 4.35% CD, the ETF's premium is 1.235 percentage points, or about $1,320 on $23,640. That sounds attractive, so she checks how sensitive it is: raising the recession probability to 30%, normal to 50% and boom to 20% drops the expected return to 3.59%, below the CD, with a deviation of 8.85%.
That reruns her question into a number she can act on: the ETF only beats the CD while she believes a recession is less likely than about one in four. Because her honest estimate sits near 30%, she puts $12,000 into the CD and keeps $11,640 for the ETF, rather than choosing one outright. Setting the goal first, the result tells her where the break-even sits, not merely which asset is nicer.
Limits of an Expected Return Estimate
Every figure the calculator returns is only as good as the inputs behind it. Probabilities are opinions, so a result such as 5.585% can look more precise than it is: the 30% recession rerun above moved the same asset to 3.59%. The result is also an average, not an outcome, so the stock market will never actually pay it in a single year, and the standard deviation does not show whether the swings are mostly gains or mostly losses. Anyone saving for retirement should treat the projection as a range, check it against a different estimate of each state, and weigh risk beside reward. The opportunity for profit comes with the potential loss of principal, which is why a careful investor reruns the scenarios, using sound finance and investing habits with the money they can afford to leave invested.
Expected Return Calculator questions
What is an expected return?
It is the probability-weighted average of the returns an investment could deliver. Multiply each possible return by its chance of occurring and add the results. It is a forecast built from your own assumptions, not a promised outcome.
How do I calculate the expected return of a stock?
List the states of the economy, give each a probability that adds up to 100%, and attach a return to each state. The sum of probability times return across all states is the expected return.
What do variance and standard deviation tell me?
They measure risk. Variance averages the squared gaps between each outcome and the expected return, and the standard deviation is its square root, in the same percentage units as the return. A larger value means a wider range of possible results.
What is a good rate of return?
It depends on the asset. Stocks have historically averaged higher returns with more swings, while bonds, CDs and high-yield savings accounts pay less with less volatility. Run a few different rates and trim the optimistic ones for a conservative estimate.
How does compounding change the result?
Compounding pays returns on earlier returns, so more frequent compounding grows the balance slightly faster, and longer holding periods amplify the effect.
How do inflation and taxes affect my return?
Inflation lowers purchasing power, so the real return is roughly (1 + nominal rate) / (1 + inflation) - 1. Taxes on gains reduce the after-tax result further.
Is the expected return guaranteed?
No. The projections are hypothetical, depend on the probabilities you enter, and carry the potential loss of principal.