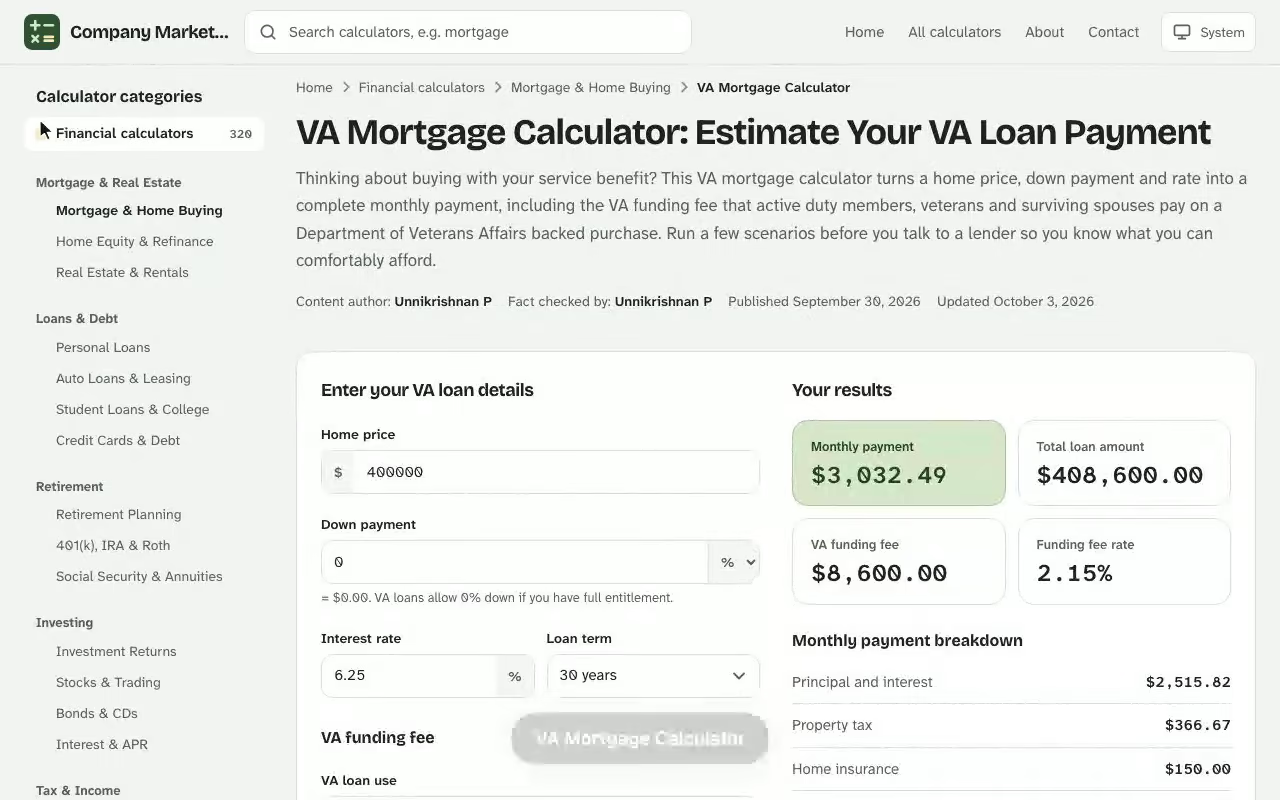
VA Mortgage Calculator. Thinking about buying with your service benefit? This VA mortgage calculator turns a home price, down payment and rate into a complete monthly payment, including the VA funding fee that active duty members, veterans and surviving spouses pay on a Department of Veterans Affairs backed purchase. Run a few scenarios before you talk to a lender so you know what you can comfortably afford. Try the free house affordability calculator to run your own numbers — everything is calculated in your browser and nothing you enter is stored or sent anywhere.
Your results
Monthly payment
–
Total loan amount
–
VA funding fee
–
Funding fee rate
–
Monthly payment breakdown
Principal and interest–
Property tax–
Home insurance–
HOA dues–
Over the life of the loan
Base loan amount–
Down payment and fee due at closing–
Total interest–
Total principal and interest–
Year-by-year schedule
Principal and interest paid each year, and the balance left. Property tax, insurance and HOA dues are not included.
Year
Principal
Interest
Ending balance
VA funding fee rates for 2026
A percentage of the loan amount, the same for Veterans, active-duty service members and National Guard or Reserve members. Rates apply to loans closed on or after April 7, 2023, as published by the Department of Veterans Affairs.
Loan type
Down payment
First use
After first use
Purchase or construction
Less than 5%
2.15%
3.3%
Purchase or construction
5% to less than 10%
1.5%
1.5%
Purchase or construction
10% or more
1.25%
1.25%
Cash-out refinance
Any
2.15%
3.3%
Interest rate reduction refinance (IRRRL)
Any
0.5%
0.5%
Manufactured home (not permanently affixed)
Any
1%
1%
Loan assumption
Any
0.5%
0.5%
Who does not pay the fee
You are exempt if you receive VA compensation for a service-connected disability, are eligible for that compensation but receive retirement or active-duty pay instead, are a surviving spouse receiving Dependency and Indemnity Compensation, have a proposed or memorandum disability rating from a pre-discharge claim, or are on active duty and show evidence of a Purple Heart before closing.
Results are estimates for educational purposes and are not financial, tax or legal advice.
How the VA mortgage calculator estimates your monthly payment
A VA home loan calculator starts with your purchase price, subtracts your down payment, adds the VA funding fee when it applies, and then spreads that loan amount over your chosen loan term at your interest rate. The result is your principal and interest. Property taxes, homeowners insurance and HOA fees are then added on top to give the estimated payment you would actually send every month. Next, open the free maximum mortgage calculator and enter your own details to see an estimate in seconds.
Your lender calculates the principal and interest portion of a fixed rate loan with the standard amortization formula:
$$M = P \times \frac{r(1+r)^{n}}{(1+r)^{n}-1}$$
Here \(M\) is the monthly principal and interest, \(P\) is the total loan amount (including any financed funding fee), \(r\) is the monthly interest rate (annual rate divided by 12) and \(n\) is the number of monthly payments.
What each input in the calculator means
Input
What it tells the calculator
Home value or purchase price
The price of the home before any down payment is subtracted.
Down payment
Cash you put toward the purchase. A VA loan needs none, but more down lowers the loan amount and the funding fee.
Interest rate
The yearly rate on the loan. A fixed rate keeps principal and interest constant for the full term.
Loan term
The repayment period, usually 15 or 30 years.
VA eligibility
Active duty or veteran, reserves or National Guard, or surviving spouse.
Used a VA loan before
First-time use or subsequent use changes the funding fee percentage.
Service-related disability
A rating of 10% or more removes the funding fee entirely.
Property taxes
Yearly real estate taxes, often estimated as a percentage of the home price.
Homeowners insurance
Yearly premium, typically a small percentage of the home value.
HOA fees
Monthly HOA dues, if the neighborhood or condo has an association.
Property taxes, homeowners insurance and HOA dues
The calculator adds three more inputs to principal and interest, because a lender expects you to budget for housing, not just the loan. Its default planning estimate is 1.2% of the home value per year for property taxes and 0.35% for homeowners insurance, though your county and insurer will set the real numbers. Hazard insurance and real estate taxes are usually collected into an escrow account, so the lender includes them in your monthly total.
VA funding fee: what it adds to a VA purchase loan
The VA funding fee is a one-time, government-backed program charge paid to the Department of Veterans Affairs to keep the VA mortgage loan program running. It replaces the private mortgage insurance that conventional lenders require, which is why a VA purchase loan has no monthly mortgage insurance. Because the program is government-backed, lenders can offer terms that build equity from day one. The funding fee depends on your down payment and on whether you have used the benefit before. Pair this with the free seller closing cost calculator for a fuller picture before you make a decision.
Down payment
First-time use
Subsequent use
Less than 5%
2.15%
3.3%
5% to less than 10%
1.5%
1.5%
10% or more
1.25%
1.25%
Other loan types carry their own percentages: an interest rate reduction refinance (IRRRL) is 0.5%, a loan assumption is 0.5%, and a manufactured home loan that is not permanently affixed is 1%. A cash-out refinance follows the same percentages as a purchase.
Disability rating and funding fee exemptions
If you have a service-related disability rating of 10% or higher, you pay no funding fee at all. Eligible surviving spouses are exempt as well. Guard and reserve members pay the same rates as active duty servicemembers and veterans. Because the fee is a percentage of the base loan, an exemption lowers both your loan balance and your monthly payment.
Financed into the loan or paid upfront
You can pay the funding fee in cash at closing (paid upfront) or have it financed into the loan. Financing keeps your cash in hand, but you pay interest on the fee for the life of the loan, so the monthly payment and the total of payments both rise.
VA mortgage payment calculator example: a $342,000 home
Here is how a VA loan calculator handles a real purchase. Suppose you are buying a $342,000 home with a 5% down payment of $17,100, a 6.375% fixed rate and a 30-year loan term. This is your first use of the benefit, and you have no disability rating. The base loan is $324,900. A 5% down payment lands in the 1.5% funding fee bracket, so the fee is $4,873.50. Financing it brings the total loan amount to $329,773.50.
Payment breakdown
Monthly amount
Principal and interest
$2,057.36
Property taxes (1.2% a year)
$342.00
Homeowners insurance (0.35% a year)
$99.75
HOA dues
$45.00
Estimated monthly mortgage payment
$2,544.11
Over 360 payments you would pay $410,875 in total interest on top of the $329,773.50 loan amount, before taxes, insurance and HOA fees.
How the example $342,000 purchase becomes a $329,773.50 VA loan once the down payment and financed funding fee are applied.
How your down payment changes a VA home loan payment
A VA loan lets you buy with no down payment, but the calculator shows why even a modest amount helps. A larger down payment cuts the base loan and also moves you into a lower funding fee bracket. Using the same $342,000 home, rate and term:
Down payment
Funding fee
Total loan amount
Monthly principal and interest
$0 (0%)
$7,353.00
$349,353.00
$2,179.51
$17,100 (5%)
$4,873.50
$329,773.50
$2,057.36
$34,200 (10%)
$3,847.50
$311,647.50
$1,944.27
Moving from no money down to 10% down trims about $235 from the monthly payment. If a disability rating exempted you from the fee on the 5% scenario, principal and interest would fall from $2,057.36 to $2,026.95, a saving of $30.40 a month.
15-year versus 30-year loan term
A shorter loan term raises the monthly payment but slashes the interest. On the $329,773.50 loan, a 15-year term costs $2,850.07 a month and about $183,239 in total interest, against $2,057.36 and $410,875 over 30 years. A 20-year term sits in between at $2,434.49 a month.
See how the VA Mortgage Calculator works: change the inputs and the monthly payment updates instantly. Enter your own numbers in the calculator above.Monthly principal and interest on the $329,773.50 loan by interest rate and loan term, with the 6.375% 30-year example outlined.
VA loan amortization schedule: where each payment goes
The calculator's amortization schedule lists every payment for your inputs and splits it into interest and principal. In month one of the example, $1,751.92 goes to interest and only $305.44 reduces your balance. The mix shifts slowly: principal first overtakes interest in month 231, and the remaining balance is $278,687 after 10 years and $182,207 after 20 years. The calculator's chart and schedule let you see this for any rate or term.
Interest dominates early payments, and principal overtakes it around year 20 of the 30-year schedule.
Extra payments and prepayment
VA loans carry no prepayment penalty, so extra payments entered in the calculator's extra payment fields go straight to principal and shorten the schedule. A biweekly payment plan, a yearly lump sum or a few extra dollars each month all reduce total interest, and you can model each one by watching the total interest figure change.
Checking a $286,900 home with a VA mortgage payment calculator
A Marine veteran with a 30% service-connected disability rating is eyeing a $286,900 house and earns $6,150 a month before taxes. The first question is whether the payment fits under the 41% debt-to-income ceiling many VA lenders use as their benchmark.
In the calculator, the home value goes in as $286,900, the down payment as $0, the interest rate as 6.125% and the loan term as 30 years. Property taxes are set at 1.1% of the price, which is $262.99 a month, and homeowners insurance at the $1,380 a year quoted by the agent, which is $115.00 a month. Under VA specifics, the disability box is ticked.
The calculator returns $1,743.23 of principal and interest with a funding fee of $0. Adding taxes and insurance gives $2,121.23 a month, or 34.5% of gross income, comfortably inside the 41% benchmark.
Next comes a second run with the disability box cleared, to see what the exemption is worth. A first-use, no-down-payment loan carries the 2.15% fee, which is $6,168.35. Financed into the loan, it lifts the balance to $293,068.35 and the principal and interest to $1,780.71, so the exemption saves $37.48 a month and about $7,324 in interest over 360 payments.
The last run stress-tests the rate. At 6.625% the principal and interest becomes $1,837.05 and the all-in payment $2,215.04, or 36.0% of income. Still under 41%, so the veteran asks a lender for a pre-approval letter that cites the Certificate of Eligibility showing the funding fee exemption, and caps the offer at $286,900.
Do you qualify for a VA mortgage loan?
To use a VA home loan you need a valid Certificate of Eligibility (COE), and your lender will usually ask for your DD 214 discharge papers. In general you qualify through one of these routes:
90 consecutive days of active duty service during wartime
181 days of active service during peacetime
More than 6 years in the National Guard or reserves
Being the surviving spouse of a servicemember who died in the line of duty or from a service-related disability
Veterans, active duty servicemembers and eligible spouses can reuse the benefit, and you do not need to be a first-time buyer. The home must be your primary residence.
Closing costs on a VA purchase loan
The funding fee is not the only cost at closing. Closing costs commonly include:
Loan origination fee, which covers the lender's processing costs
Discount points, paid to buy a lower rate; two points (2%) or less is considered reasonable
Credit report fee, which is not refunded if the loan never closes
Appraisal fee, because the VA sets the reasonable value of the property
Title insurance, to confirm there are no liens against the home
Recording fee, to record the deed
Hazard insurance and real estate taxes for the first year
The estimated payment leaves these costs out, apart from a financed funding fee, so budget them separately as cash needed at closing. Sellers may pay some or all of these through seller concessions, up to 4% of the loan, but they are not obligated to.
Pros and cons of a VA home loan
Advantages over FHA and conventional loans
Each of these shows up in the calculator's results as a lower monthly payment or a different loan balance.
No down payment, while a conventional loan normally asks for 5% and an FHA loan 3.5%; USDA is the only other common zero-down option
No monthly mortgage insurance, and typically lower interest rates and closing costs
VA appraisals help protect you from overpaying
A loan assumption lets a qualified buyer take over your loan later
Excellent refinance programs, including an IRRRL and a cash-out refinance
Limits to keep in mind
The first limit is the only one the calculator can price directly, through its funding fee input.
The funding fee can be expensive when you are not exempt
The loan cannot pay for planned home improvements, so a true fixer-upper is hard to finance
It covers owner-occupied homes only, not investment property or vacant land
Not every seller or lender has experience with VA paperwork, so choose a specialist
Ways to lower your VA mortgage payment
Once you see your number, a few levers change it quickly. Improve your credit score before applying, since the VA sets no minimum but lenders do. Shop several lenders for the lowest interest rate and compare APR, which folds in fees. Put more down if you can, extend the term if you need breathing room, and weigh an affordability check against your budget and your military housing allowance (BAH). If you already own, remember that a home sale can supply the down payment, and that the VA loan limit mostly matters when you have an existing VA loan.
The figures here are for educational purposes only. Your lender's loan officer can confirm your rate, fees and approval. Run your own numbers through this VA mortgage loan calculator again whenever rates, prices or your down payment change.
VA Mortgage Calculator questions
How do I calculate a VA mortgage payment?
Take the home price, subtract your down payment, add the VA funding fee if you are not exempt, and spread that loan amount over the loan term at your interest rate. Then add property taxes, homeowners insurance and any HOA fees to the principal and interest.
What is the VA funding fee?
It is a one-time fee paid to the Department of Veterans Affairs on most VA loans. For a purchase it is 2.15% on first use with less than 5% down, 1.5% with 5% to under 10% down and 1.25% with 10% or more down; subsequent use with less than 5% down is 3.3%.
Who is exempt from the VA funding fee?
Veterans with a service-related disability rating of 10% or more and eligible surviving spouses do not pay the fee. Select the disability option in the calculator to see the payment without it.
Is a down payment required on a VA loan?
No. Most eligible borrowers can buy with no down payment, but putting money down shrinks the loan amount and can drop you into a lower funding fee bracket.
Should I finance the funding fee or pay it upfront?
Financing keeps cash in your pocket at closing but adds the fee to the loan, so you pay interest on it. Paying it upfront lowers the monthly payment and the total interest.
Does the monthly payment include closing costs?
No. The estimate covers principal and interest, property taxes, insurance, HOA fees and any other yearly costs you enter. Closing costs such as origination fees, appraisal and title insurance are paid separately, unless a seller concession covers them.
Do VA loans have private mortgage insurance?
No. VA loans do not require monthly mortgage insurance, which is one reason the payment is often lower than a comparable conventional or FHA loan.
Can I pay off a VA loan early?
Yes. VA loans carry no prepayment penalty, so extra monthly, yearly or one-time payments reduce the balance and total interest. Enter them under extra payments to see the new payoff time.