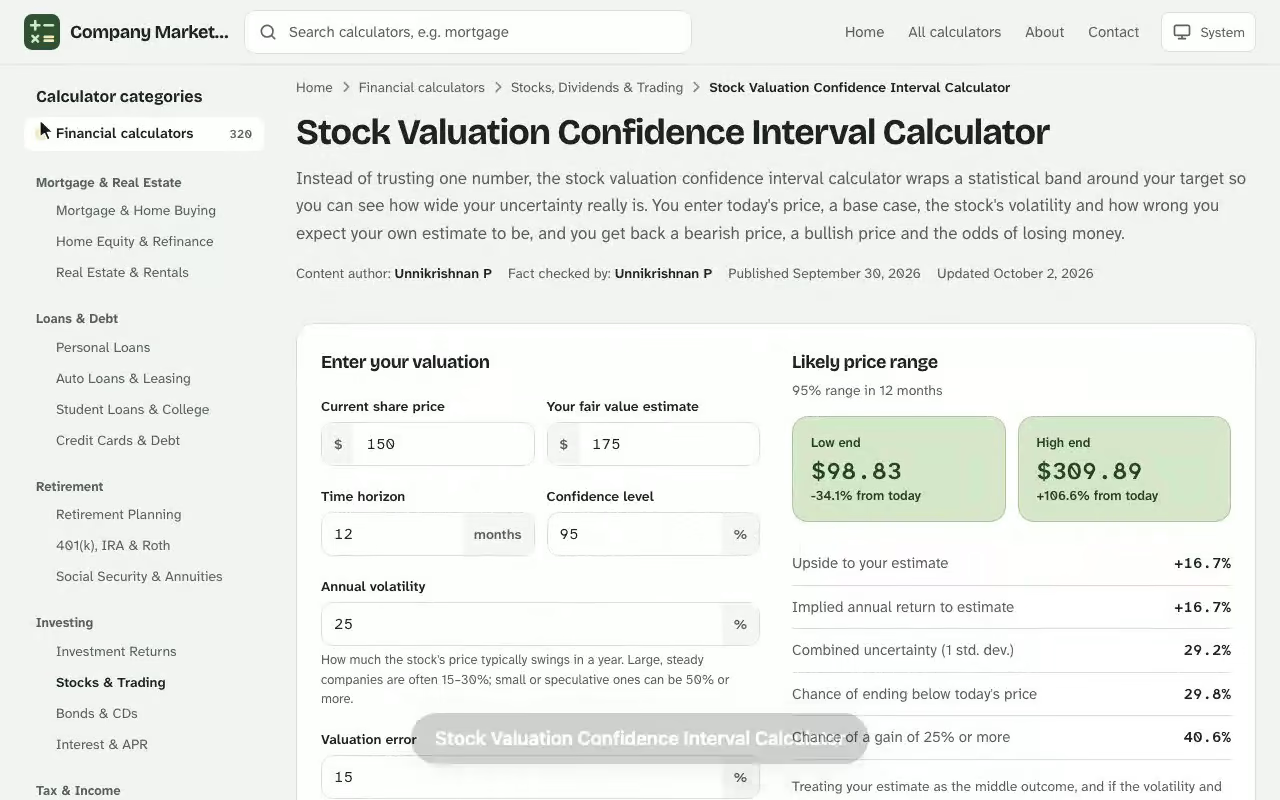
Stock Valuation Confidence Interval Calculator. Instead of trusting one number, the stock valuation confidence interval calculator wraps a statistical band around your target so you can see how wide your uncertainty really is. You enter today's price, a base case, the stock's volatility and how wrong you expect your own estimate to be, and you get back a bearish price, a bullish price and the odds of losing money. The pivot point calculator online is free to use with no sign-up, and works on desktop and mobile.
Likely price range
–
Low end
–
–
High end
–
–
Upside to your estimate
–
Implied annual return to estimate
–
Combined uncertainty (1 std. dev.)
–
Chance of ending below today's price
–
Chance of a gain of 25% or more
–
Range at other confidence levels
Higher confidence means a wider range. Changes are measured from today's price.
Confidence
Low
Change
High
Change
Chance of finishing above a price
Move from today
Price
Chance of ending above it
Results are estimates for educational purposes and are not financial, tax or legal advice.
Stock Valuation Confidence Interval Calculator. Instead of trusting one number, the stock valuation confidence interval calculator wraps a statistical band around your target so you can see how wide your uncertainty really is. You enter today's price, a base case, the stock's volatility and how wrong you expect your own estimate to be, and you get back a bearish price, a bullish price and the odds of losing money. The pivot point calculator online is free to use with no sign-up, and works on desktop and mobile.
Stock Valuation Confidence Interval Calculator: How the Price Range Is Built
A confidence interval is a statistical range that is expected to contain the future outcome a stated share of the time. For a share price, that means a lower price and an upper price with a probability attached, so a 90% confidence interval says that nine times out of ten the stock should finish between the two. Pair this with the market cap growth calculator online for a fuller picture before you make a decision.
The tool takes six inputs: the current stock price, a base case value from your own research, annual historical volatility, your estimation error, the time horizon in months and the confidence level. It treats the base case as the centre of a bell curve and sets the width of that curve from two sources of doubt, which keeps the output honest about both the market and your model.
The two sources of spread
Market noise grows with time: a stock that swings 24% a year moves less over three months than over three years. Model doubt is the chance your own estimate is simply off, expressed as a percentage of the base case. Combining them gives one standard deviation for the whole horizon.
The core formulas
The horizon spread blends annual volatility, scaled by elapsed time, with your estimation error:
The lower and upper prices then sit a critical value away from the base case on each side:
$$\text{Lower} = B - z \times B \times \sigma_H \qquad \text{Upper} = B + z \times B \times \sigma_H$$
Here \(B\) is the base case, \(T\) is months, \(e\) is the estimation error and \(z\) is the z-score for your confidence level. The chance of finishing below today's price comes from the same bell curve:
$$P(\text{loss}) = \Phi\left(\frac{\ln(P_0) - \ln(B)}{\sigma_H}\right)$$
The two formulas behind the interval, filled in with the worked example's own inputs.
Calculating Confidence Intervals for a Stock Price Target
Whenever you are calculating confidence intervals for a share, the logic is the same as the textbook version for a sample: an estimate, plus or minus a margin of error. The difference is that a stock has no sample to average, so volatility and your own forecast error play the part of the standard error. Next, open the capm calculator and enter your own details to see an estimate in seconds.
Step-by-step method
Collect the current stock price, your base case and the annual volatility, expressed as a percentage.
Decide how many months ahead the estimate applies, then choose the estimation error that matches your research quality.
Scale volatility to the horizon and combine it with the error to get the horizon spread.
Look up the critical value for your confidence level and multiply it by the spread to get the margin of error in dollars.
Subtract and add that margin to the base case to get the lower bound and the upper bound.
Where to find historical volatility
Most brokerage platforms show 30-day and one-year volatility on the quote page. You can also take the standard deviation of daily returns over the last year and multiply it by the square root of 252 trading days. Use the annualised figure, because the tool rescales it to your time horizon.
Choosing a Confidence Level: 80%, 90%, 95% or 99%
The confidence level is the probability the interval is built to capture. Raising it pulls in more of the tail, so the range gets wider but the claim gets stronger. The table below applies each level to one set of inputs, a $71.80 base case with an 18.76% horizon spread.
Confidence level
Critical value (z)
Lower bound
Upper bound
Typical use
80%
1.282
$54.54
$89.06
Quick screening
90%
1.645
$49.64
$93.96
Everyday planning
95%
1.960
$45.40
$98.20
Standard reporting
99%
2.576
$37.10
$106.50
Stress testing
A 95% confidence interval is the usual convention, but the extra width is not free: the jump from 90% to 99% adds roughly $14 of range. Choose the level that fits the cost of being wrong, not the one that makes the chart look tidy.
Worked Example: A 90% Confidence Interval on a $71.80 Base Case
Suppose a stock trades at $62.40 and your research points to a base case of $71.80 six months from now. Historical volatility is 24% a year, you allow an estimation error of 8%, and you want a 90% confidence level.
Standard deviation in dollars: \(71.80 \times 0.1876 = \$13.47\)
Critical value: 1.645 for a two-sided 90% interval
Margin of error: \(1.645 \times 13.47 = \$22.16\)
The tool therefore returns a bearish price of $49.64 and a bullish price of $93.96, which is a move of -20.4% to +50.6% from today's price. Your base case sits at +15.1%. Each tail holds 5%, so there is a 5% chance of finishing below $49.64 and a 5% chance of finishing above $93.96.
Key probabilities from the same inputs
Outcome
Probability
What it tells you
Finishing below $62.40
22.7%
Your probability of loss
Reaching the $71.80 base case
50.0%
The centre of the curve
Gaining 25% or more (above $78.00)
32.9%
Real upside potential
Even with a positive base case, roughly one outcome in four ends in a loss. That is information a single target never shows you.
Probability split around today's price for the worked example.
How Time Horizon and Estimation Error Widen the Margin of Error
The width of the band is driven by two dials, and they behave differently. Stretching the time horizon adds market noise gradually, while a larger estimation error adds a fixed block of doubt no matter how short the window is. The table keeps the same price, base case and volatility and varies only the months, at a 90% confidence level.
Months ahead
Horizon spread
Lower bound
Upper bound
Probability of loss
1
10.58%
$59.30
$84.30
9.2%
3
14.42%
$54.77
$88.83
16.5%
6
18.76%
$49.64
$93.96
22.7%
12
25.30%
$41.92
$101.68
29.0%
24
34.87%
$30.62
$112.98
34.4%
The same stock's 90% price range keeps widening as the time horizon lengthens.
Why a wider interval is not a flaw
A wider interval after 24 months is not the model failing; it is the model admitting that two years of market movement are harder to predict than one month. A narrower interval that ignores this would look more precise and be less true.
Setting a realistic estimation error
If your base case comes from a detailed model built on audited earnings, a single-digit estimation error is defensible. If it rests on a rough multiple of next year's sales, use 15% or more. Published research on analyst forecasts consistently shows misses larger than most investors assume, so lean high when unsure.
Interval Estimation vs Point Estimates in Equity Analysis
A traditional target is one of the point estimates that analysts publish in a note. It is easy to quote and easy to act on, which is exactly why it misleads: it implies a certainty that no forecast of a stock price has ever earned.
False precision and model uncertainty
A $71.80 target looks sharper than a $50-to-$94 range, but the range is the more accurate statement. Treating the first as exact is false precision, and ignoring model uncertainty means your discounted cash flow or multiple-based work quietly assumes every input is right.
Using the range for risk management and position sizing
The lower bound turns a vague worry into a number you can plan around. Many investors cap the loss they will tolerate on one idea and size the holding so that the bearish price stays inside that cap. That is practical risk management, and it is the simplest form of position sizing built on a probability range.
Reading the Confidence Interval Output: A 95% Interval on a $258.70 Target
An investor holds a watchlist name at $238.15. Her model gives a base case of $258.70 in 15 months, and she decides she will not enter if the downside exceeds 25% of the entry price, which is $178.61. From the stock's quote page she takes 14% annual volatility, then enters 5% as the estimation error because the model leans on one segment's margin forecast, picks 95% and clicks Calculate.
The result is a range of $175.38 to $342.02. The lower bound sits 26.4% below the entry price, so it breaches her 25% rule, and the probability of loss shows 30.7%. The expected gain to the base case is only +8.6%, which is thin against that downside.
She reruns the confidence interval calculation with a 12-month horizon, since her catalyst, the next annual guidance, lands within a year. The new range is $183.32 to $334.08, a 23.0% drop at the bottom, which clears her 25% rule. She decides to buy half her intended position now and add after the guidance, so the confidence interval changed the size of the purchase rather than the decision to look at it.
How to Calculate a Confidence Interval for a Population Mean, and How the Price Tool Differs
In finance and statistics alike, the classical case is the template, and the price tool borrows its structure from it, with horizon volatility and your estimation error playing the part of the standard error, so that case is worth seeing on its own. Suppose you want the average one-year return across large-cap stocks, a population you can never fully observe. You draw a random sample of 64 names and find a sample mean of 9.4% with a sample standard deviation of 17.2%. This is sampling in its simplest form: you measure a few and infer the many.
See how the Stock Valuation Confidence Interval Calculator works: change the inputs and the low end updates instantly. Enter your own numbers in the calculator above.
To calculate a confidence interval here, divide the deviation by the square root of the sample size to get a standard error of \(17.2 / \sqrt{64} = 2.15\%\). With 64 observations you can use the critical z-value of 1.96, so the margin of error is \(1.96 \times 2.15 = 4.21\%\). The 95% confidence interval for the population mean runs from 5.19% to 13.61%, and the mean of 9.4% sits in the middle of that band.
More data is the classical way to tighten the band: quadruple the sample size to 256 and the standard error halves to 1.08%, so the interval shrinks to 7.29%-11.51%. The price tool has no sample-size input; its band narrows only when you shorten the time horizon or lower your estimation error.
What a 95% interval does and does not say
A common misreading is that there is a 95% chance the true value sits inside this particular band. The correct reading is about the method: if you repeated the sampling many times, about 95% of the intervals you built would capture the true value of the mean. Each single interval either contains it or does not, which is why the width matters more than the label.
Margin of error and accuracy in practice
In the price tool, the margin of error is the critical value times the dollar standard deviation, which is the $22.16 half-width in the worked example, and it is the clearest summary of accuracy the output offers. A tight margin does not make an estimate right; it makes it a more precise estimate. A biased base case or volatility input shifts the whole band, so check where each input came from before you trust the width.
Linking the sample case back to price ranges
In the price tool, volatility and estimation error stand in for the standard error, and the output is a probability distribution over future prices instead of over a sample mean. The result is a valuation range you can compare with the current quote, and it shows the downside risk in dollars rather than in adjectives. For any investment you are weighing, that is the figure to put next to the upside, and any calculator that shows only the midpoint is hiding half the story.
Limits of the Normal Distribution and a Statistics Cross-Check
The model assumes a normal distribution of outcomes, so it cannot see a bankruptcy, a takeover or a gap after earnings. Real returns have fatter tails than the bell curve, which means the true chance of an extreme move is larger than the interval implies.
A t-interval for a stock's average return
The price calculator applies a z-score to the horizon spread rather than a t-interval to past returns, but the classical version is a useful cross-check on a stock's history, and average returns are the standard case in introductory statistics. Say you collect 40 monthly returns with a sample mean of 1.3% and a sample standard deviation of 6.1%. The standard error is \(6.1 / \sqrt{40} = 0.96\%\).
Because the population standard deviation is unknown, you use the t-distribution with 39 degrees of freedom, giving a critical value of 2.023. The margin is \(2.023 \times 0.96 = 1.95\%\), so the 95% interval for the true mean is -0.65% to +3.25%. It straddles zero, which tells you 40 months of data cannot prove the stock has a positive average return.
A large sample or a known population variance lets you use the z-score of 1.96 instead. The interval narrows as the sample size grows. The two-sided choice puts the leftover probability in two tails, with 2.5% in each; a test on one tail puts all of it on one side. If the interval for an average return excludes zero, hypothesis testing would reject a true mean of zero at that level, but for price ranges you read the bounds directly and interpret them as scenarios for the calculator's output, not predictions.
Practical Tips for Interpreting Your Results
Treat every confidence interval as a conversation with your assumptions rather than a forecast. A few habits make the numbers more useful:
Change one input at a time in the calculator so you can see which one drives the confidence interval; for most stocks it is volatility, not the base case.
Compare the probability of loss against your own tolerance before you look at the upside.
Pair the output with fundamental analysis of the company's valuation: the interval tells you how wrong you can be, not whether the thesis is right.
Revisit the numbers when earnings, rates or volatility change, because the band moves with each of them.
Check the bearish price against your risk exposure across the whole portfolio, not stock by stock.
Used this way, a confidence interval supports better investment decisions without pretending to remove uncertainty. It cannot predict the next quarter, but it can show whether your price targets deserve the confidence you have been giving them, and how much you stand to lose when they miss.
It is a statistical range around your price target. Instead of one number, you get a lower and an upper price plus the probability that the stock finishes between them at the end of your time horizon.
How do I interpret the bearish and bullish prices?
The bearish price is the lower bound and the bullish price is the upper bound of the interval. At a 90% confidence level, each tail holds 5%, so there is a 5% chance of finishing below the bearish price and a 5% chance of finishing above the bullish price.
Where do I find historical volatility for a stock?
Most brokerage and charting platforms show it on the quote or statistics page. You can also take the standard deviation of daily returns over the past year and multiply it by the square root of 252 trading days to annualise it.
What confidence level should I use?
90% to 95% is the usual range. A higher level widens the interval and makes the claim stronger; a lower level gives a tighter range that is wrong more often. Choose based on how costly a miss would be.
What is estimation error and how do I set it?
It is the percentage by which your own base case could be wrong. A detailed model built on audited earnings may justify a single-digit figure; a rough multiple of next year's sales deserves 15% or more.
Why does the range get wider with a longer time horizon?
Market volatility accumulates over time, so a stock is harder to predict two years out than one month out. The estimation error does not shrink with time either, so long horizons carry the most uncertainty.
How accurate is this confidence interval model?
It assumes normally distributed outcomes around your base case, so it cannot see events like takeovers, bankruptcies or earnings gaps. Real returns have fatter tails, so treat the range as a guide, not a guarantee.