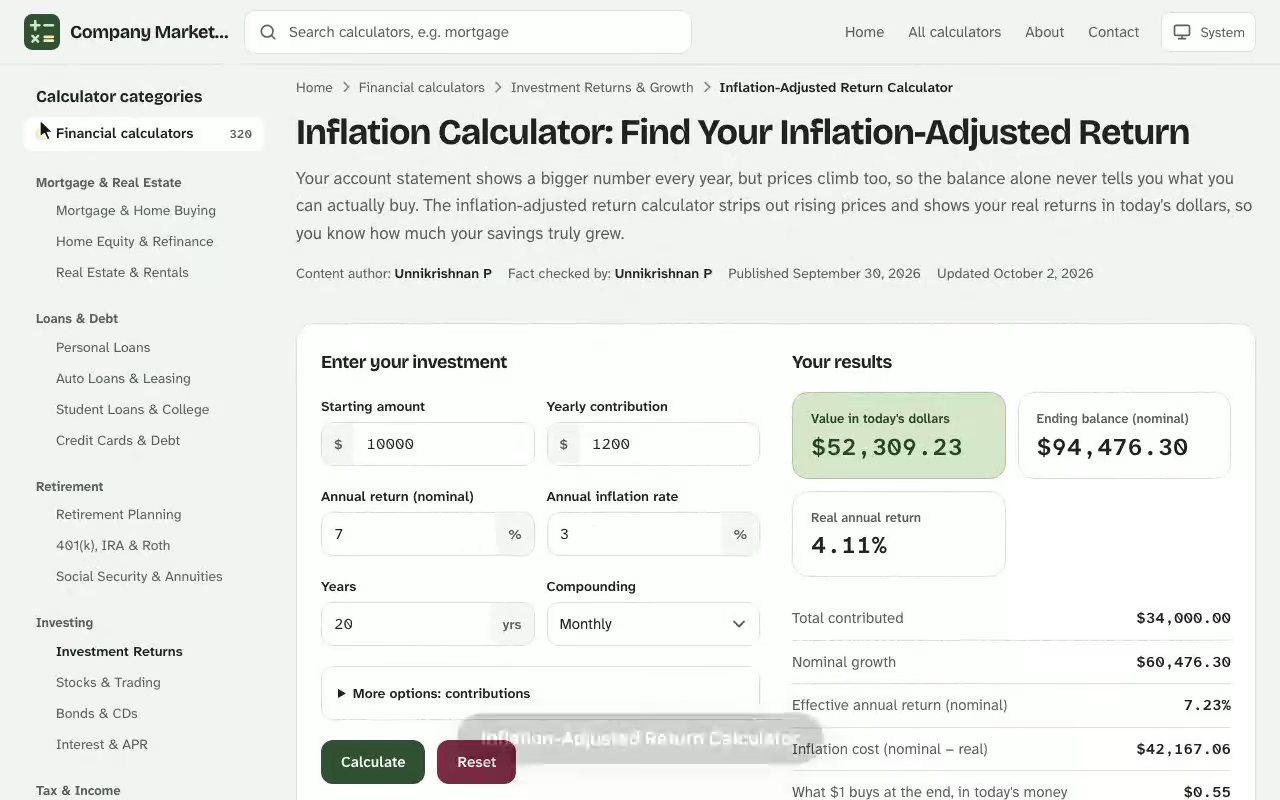
Inflation-Adjusted Return Calculator. Your account statement shows a bigger number every year, but prices climb too, so the balance alone never tells you what you can actually buy. The inflation-adjusted return calculator strips out rising prices and shows your real returns in today's dollars, so you know how much your savings truly grew. The investment loan calculator is free to use with no sign-up, and works on desktop and mobile.
Your results
Value in today's dollars
–
Ending balance (nominal)
–
Real annual return
–
Total contributed
–
Nominal growth
–
Effective annual return (nominal)
–
Inflation cost (nominal − real)
–
What $1 buys at the end, in today's money
–
Year-by-year: nominal vs real
The real balance is the nominal balance divided by the price level after that many years of inflation.
Year
Contribution
Nominal balance
Real balance
Cumulative inflation
Results are estimates for educational purposes and are not financial, tax or legal advice.
Inflation-Adjusted Return Calculator. Your account statement shows a bigger number every year, but prices climb too, so the balance alone never tells you what you can actually buy. The inflation-adjusted return calculator strips out rising prices and shows your real returns in today's dollars, so you know how much your savings truly grew. The investment loan calculator is free to use with no sign-up, and works on desktop and mobile.
What an Inflation-Adjusted Return Calculator Measures
A nominal figure is the number printed on your statement. A real figure is that same number after you remove the effect of rising prices. Everything this tool does comes down to converting one into the other, using the annual inflation rate you expect over the life of the investment. Feed it an initial investment, an expected annual return, an investment duration, and an optional annual contribution, and it returns two balances: what the account will say, and what that balance will be worth in today's dollars. Try the free broad portfolio questionnaire to run your own numbers — everything is calculated in your browser and nothing you enter is stored or sent anywhere.
Think of it as an investment inflation calculator that answers one practical question: after prices rise, did the money you put to work actually gain purchasing power? Plain growth rates cannot answer that. A fund that earns 6% in a year when prices rise 6% leaves you exactly where you started, whatever the statement says.
Who gets the most from it
Long-term savers comparing an account's growth against the cost of living
People in retirement planning who need a target balance expressed in money they understand today
Any investor judging whether a fund's promised yield really beats the inflation rate
Anyone comparing several investments on an equal, price-adjusted footing
Anyone who wants to see how much a few extra points of inflation change the picture
Real Returns vs Nominal Return: Why the Gap Matters
A nominal return is the headline percentage a fund, bond or savings product reports. The real return is what remains once the price level has risen. The difference between them is not a rounding detail: over a decade or two, it can erase a third or more of the apparent nominal gain.
Inflation works quietly. Because a basket of everyday goods costs a little more each year, each dollar you hold buys slightly less. That erosion of buying power compounds just as growth does, which is why the real rate of return on a long holding period looks so different from the number advertised on the brochure. Measuring real growth rather than headline growth is the entire point of running this calculation.
See how the Inflation-Adjusted Return Calculator works: change the inputs and the value in today's dollars updates instantly. Enter your own numbers in the calculator above.
The simple subtraction shortcut and where it falls short
Many people subtract inflation from the nominal return and call the answer the real rate. With a 6.4% return and 3.1% inflation that gives 3.3%. The exact result is 3.20%. The gap looks small in one year, but it widens as the rates and the horizon grow. The calculator uses the exact method, shown in the next section, so you do not have to rely on the shortcut.
Inflation Calculator Formula for Real Value
Three short formulas drive the whole tool. Learn them once and you can check any result by hand.
The real return formula
The exact real return divides the growth factor by the price factor, where r is the nominal annual return and i is the annual inflation rate, both as decimals:
$$\text{Real return} = \frac{1 + r}{1 + i} - 1$$
Future value with an annual contribution
Your account's future value combines the lump sum compounding for n years with the stream of deposits. Here PV is the starting balance and C is the yearly deposit made at each year end:
Deflating that balance by the cumulative price increase gives the figure in today's dollars:
$$\text{Real value} = \frac{FV}{(1 + i)^{n}}$$
Inflation rate formula and CPI
Where does the annual inflation rate come from? In the United States, the consumer price index (CPI) tracks the cost of a fixed basket of goods and services each month. The inflation rate formula compares two readings of that price index:
A consumer price index reading for one month means little alone, so analysts compare it with the reading a year earlier. Whenever you do not have a forecast of your own, a long-run CPI average is the most defensible starting assumption.
Worked Example: Inflation-Adjusted ROI on a 15-Year Investment Account
Suppose you open an investment account with $42,500 and add $3,000 at the end of every year for 15 years. You assume a 6.4% annual return and 3.1% average inflation, with deposits made once per year. Plugging those inputs into the formulas above:
The lump sum grows to $42,500 × 1.06415 = $107,774.
The fifteen deposits grow to $3,000 × ((1.06415 − 1) ÷ 0.064) = $71,993.
The nominal future value is therefore $179,767, against $87,500 actually paid in.
Prices rise by 1.03115 = 1.5808 over the period, so the same balance is worth $179,767 ÷ 1.5808 = $113,718 in today's dollars.
The exact real return is (1.064 ÷ 1.031) − 1 = 3.20% a year. Your inflation-adjusted roi is the real gain over the money you paid in: $113,718 − $87,500 = $26,218, while the nominal gain looks like $92,267. In other words, inflation consumed roughly $66,000 of the apparent profit, leaving real profits of $26,218 and an inflation adjusted balance of $113,718.
Year
Amount paid in
Nominal balance
Value in today's dollars
5
$57,500
$75,003
$64,385
10
$72,500
$119,326
$87,932
15
$87,500
$179,767
$113,718
Notice how the third column trails the second more and more each year. That widening spread is the cost of inflation made visible, and it is what a real investment return calculator exists to show.
How the inflation assumption changes the result
Run the same inputs with a lower or higher average inflation figure and the outcome moves sharply. At 2.1% inflation the final balance is worth $131,621 in today's dollars, a real return of 4.21%. At 4.6% it falls to $91,566, a real return of only 1.72%. The nominal balance is identical in all three runs; only the purchasing power differs. Testing a low, middle and high case is a better habit than trusting a single guess.
How the Investment Inflation Calculator Inputs Work
Each field maps to a symbol in the formulas. Knowing what to type removes most input mistakes.
Initial investment (PV)
The principal you start with. Use zero if you are only making regular deposits.
Expected annual return
The annual interest rate or growth rate you assume, sometimes called the stated rate because it is quoted before inflation. Use a conservative figure rather than last year's best fund result.
Annual inflation rate
The yearly rise in prices you expect across the holding period. This is the single most influential assumption you make.
Investment duration
How many years the money stays invested. Decimals work, so 7.5 years means seven years and six months.
Annual contribution
The optional yearly top-up. These periodic deposits are what turn a modest account into a large one over time.
Checking a Kitchen Fund with the Real Investment Return Calculator
A homeowner wants $24,000 of buying power eight years from now for a kitchen renovation. Today, $18,750 sits in a balanced fund that has averaged 5.2% a year, and the statement says it will reach about $28,000. That sounds comfortable, but the contractor's quote is in today's money, so the comparison has to be in today's money too.
The homeowner opens the calculator and enters an initial investment of $18,750, an expected return of 5.2%, an investment duration of 8 years, no annual contribution, and an inflation assumption of 2.7%, taken from the recent average on the consumer price index chart for the household's own spending categories.
The tool returns two balances. The nominal balance is $28,127. The same balance expressed in today's dollars is $22,728, which works out to a real return of 2.43% a year. That is below the 3% planners often use as a minimum, and it leaves the goal $1,272 short of $24,000.
The homeowner changes one input at a time. Raising inflation to 3.4% cuts the real balance to $21,526, so the plan has little room for a hot stretch of price increases. Next, working backwards, the homeowner finds that hitting $24,000 at 2.7% requires a nominal balance of $29,701, which means starting with $19,799 rather than $18,750.
The decision is specific: move $1,050 from the checking account into the fund this month, then rerun the same inputs with 3.4% inflation next January to see whether the margin holds. The statement figure of $28,127 never changed, but the real figure now points to a clear action.
Choosing an Annual Inflation Rate: Historical Context
You rarely know future inflation, so you pick an estimate. The historical context helps. Over the long term, United States inflation has averaged roughly 3% a year, with deflation during the early 1930s and sharp spikes in the 1970s and again in 2022. The Federal Reserve aims to keep inflation near 2%, which is why many planners use 2% to 3% as a base case and test 4% or higher as a stress case.
Why prices rise
The cause of a price surge decides how long it lasts, and therefore which figure belongs in the calculator's inflation field. A short spike justifies a higher rate over a few years; a structural cause justifies a higher rate for the whole horizon. Economists usually separate four types:
Demand-pull inflation appears when buyers want more goods than the economy can supply.
Cost-push inflation follows when production and shipping costs rise and sellers pass them on.
Built-in inflation arises when wages and prices chase each other upward.
Monetary inflation reflects more money circulating than there are goods and services to buy.
Averages hide the path
A fifteen-year average of 3.1% can hide several years at 1% and several at 7%. Because the calculator applies one steady rate, treat the output as a planning estimate. If you are close to withdrawing the money, run shorter periods with the specific years you expect.
Protecting Purchasing Power in Your Investment Portfolio
To beat inflation over many years, you have to widen the real number you just measured. Four approaches come up repeatedly with long-held investments:
Hold inflation-linked bonds, such as TIPS, whose principal adjusts with the CPI.
Diversify into real assets like property or commodities, which tend to follow prices.
Own stocks and other investments, including a broad mutual fund for growth that has historically outpaced price increases over decades.
Reinvest gains so that the power of compounding works on a larger base.
A rule of thumb many advisors give is to aim for a real return above 3% if you want meaningful wealth over a long term horizon. Our example sits at 3.20%, just above that line.
Weighing compound interest against rising prices
Compound interest and rising prices are the same mathematics pulling in opposite directions, and the two balances the calculator returns are that contest made visible. In the 15-year example, compounding lifts the account to $179,767, while the price level cuts what it can buy to $113,718. Starting earlier and depositing steadily widens the gap between those two numbers in your favour.
Common Mistakes When Reading Real Returns
Comparing a fund's nominal yield with a savings goal stated in today's money, or quoting inflation-adjusted returns for one fund and headline yields for another.
Using last year's inflation figure for a twenty-year projection.
Ignoring fees and tax drag, which lower the real figure further.
Forgetting that withdrawals during retirement also need to rise with prices.
If a bond's maturity payout is promised in fixed money, compare its redemption value against the price-adjusted principal rather than against the amount you originally invested. A fund beating its original principal can still lose against the future cost of what that money would have bought.
When you need a clear plan, a financial advisor can turn these estimates into a workable financial plan, since the calculation here does not account for individual tax rules, fees or market swings. Use it to compare scenarios and frame your savings goals, then test your assumptions against more than one possible outcome. For other investment math, browse finance calculators at Joteo.
Inflation-Adjusted Return Calculator questions
What is an inflation-adjusted return?
It is the growth of an investment after the loss of purchasing power from rising prices is removed. A 7% gain in a year with 3% inflation is only about 3.9% in real terms.
How do I calculate real return after inflation?
Divide one plus your nominal return by one plus the inflation rate, then subtract one. For example, (1.064 / 1.031) - 1 gives about 3.20% a year. The calculator does this for you and also compounds regular contributions.
Why is the real value lower than my account balance?
Your balance is stated in future dollars. Prices rise each year, so the same amount buys less. The Value in Today's Dollars divides your balance by the cumulative price increase to show what it could buy at current prices.
Which inflation rate should I use?
Use a long-run average rather than one year's reading. Many planners start with 2% to 3%, then test a higher case such as 4% to see how sensitive the result is.
Does the calculator include taxes and fees?
No. Enter a return that is already net of fund fees, and remember taxes will lower the real result further depending on your account type.
Can I model withdrawals in retirement?
Yes. Switch Regular Contributions to Withdrawals and set an amount and frequency. The calculator subtracts each withdrawal as the balance compounds.
How can I protect my returns from inflation?
Common approaches include inflation-linked bonds such as TIPS, diversifying into real assets, holding equities for long-term growth and reinvesting returns so they compound.
What real return should I aim for?
A common rule of thumb is a real return above about 3% a year for meaningful long-term wealth building, though your own goals and risk tolerance matter more than any single threshold.