Fixed Rate Mortgage vs. Interest-Only Mortgage Calculator
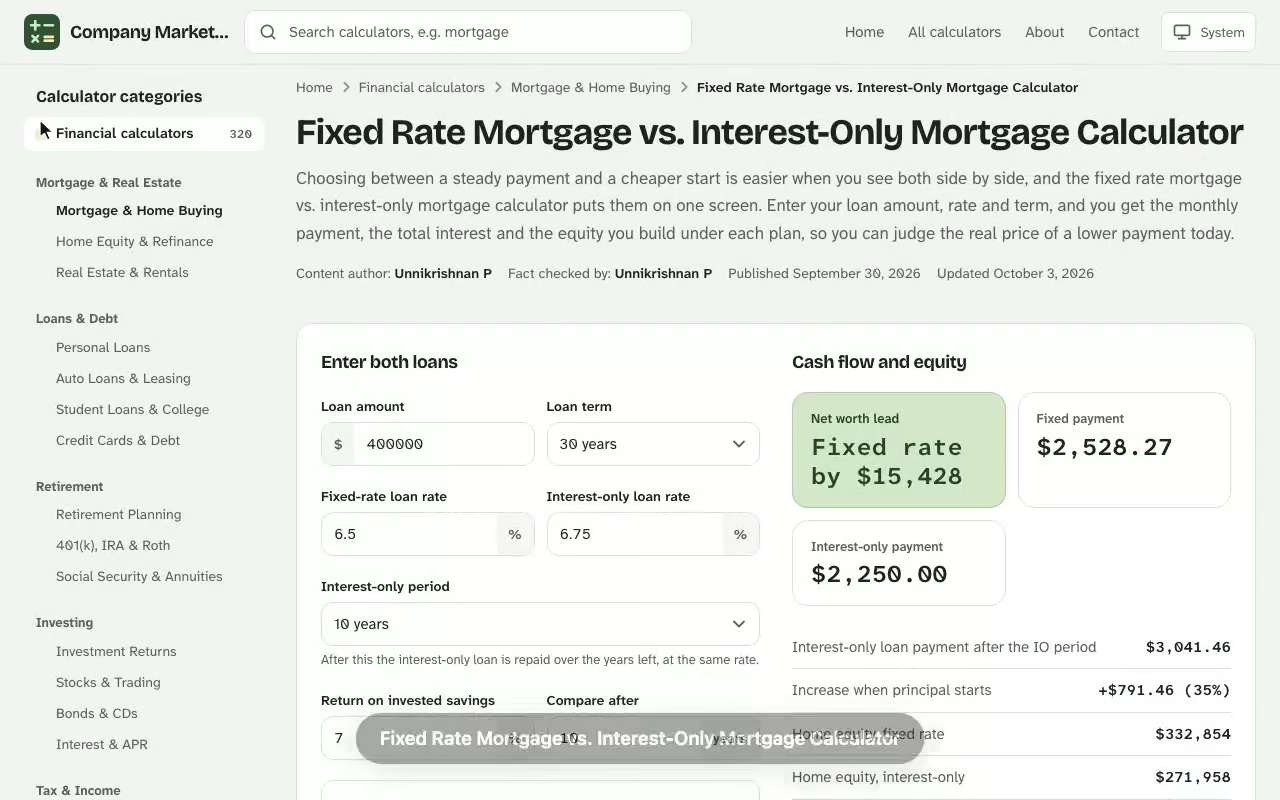
Fixed Rate Mortgage vs. Interest-Only Mortgage Calculator. Choosing between a steady payment and a cheaper start is easier when you see both side by side, and the fixed rate mortgage vs. interest-only mortgage calculator puts them on one screen. Enter your loan amount, rate and term, and you get the monthly payment, the total interest and the equity you build under each plan, so you can judge the real price of a lower payment today. If you want to see how the figures change, the free amortization calculator gives you an instant result you can adjust as you go.
Cash flow and equity
Net worth lead
–
Fixed payment
–
Interest-only payment
–
Interest-only loan payment after the IO period–
Increase when principal starts–
Home equity, fixed rate–
Home equity, interest-only–
Investments, fixed rate (after tax)–
Investments, interest-only (after tax)–
Equity + investments, fixed rate–
Equity + investments, interest-only–
Interest paid, fixed rate–
Interest paid, interest-only–
Return where both finish level–
–
Both households spend the larger of the two payments each month and invest whatever their own loan does not need. Results are at the end of year –.
Year-by-year cash flow and equity
Payments made each year, home equity and invested savings for both loans.
Year
Fixed payments
IO payments
Fixed equity
IO equity
Fixed investments
IO investments
Ahead
Results are estimates for educational purposes and are not financial, tax or legal advice.
How the Fixed Rate Mortgage vs. Interest-Only Mortgage Calculator Works
A fixed-rate loan keeps one rate and one payment from the first month to the last. Each payment covers that month's interest and a slice of the balance, so the balance shrinks every month. An interest-only mortgage works differently: during a set window you pay only the interest charges, and the balance does not move. When the window closes, the lender recalculates the payment to clear the full balance over the years that remain. Try the balloon loan calculator to run your own numbers — everything is calculated in your browser and nothing you enter is stored or sent anywhere.
That difference is why the two plans cannot be judged by the first payment alone. The calculator runs both schedules to the end and reports what each one costs. Lenders sometimes shorten the label to an IO loan, and the comparison holds whichever name appears on your offer, because the only question is how your monthly mortgage payment changes over time and what it buys you in ownership.
Monthly payment makeup on the $412,500 example: $2,567 fixed, $2,355 interest-only, then $3,161 after the reset.
Inputs You Enter
Loan amount: the home price minus your down payment.
Loan term: the total number of years, usually 15, 20, 25 or 30.
Interest rate for the fixed plan, and the rate quoted on the interest-only plan, which is often a little higher.
Interest-only period: how many years you pay interest alone before principal payments begin.
Results You Get Back
The monthly payment on the fixed plan.
The monthly payment during the interest-only period and the higher payment after it.
Total payments and total interest for both loans, plus the balance left after the initial period.
Press the calculate button and the comparison appears instantly, so you can change one input at a time and watch what moves.
Fixed-Rate Mortgage Formula: The Stable Payment
A conventional mortgage with a fixed rate uses the standard amortization formula, where \(P\) is the loan amount, \(i\) is the monthly rate (the annual rate divided by 12) and \(n\) is the number of payments: If you want to see how the figures change, the interest only arm calculator online gives you an instant result you can adjust as you go.
$$M = P \times \frac{i}{1 - (1 + i)^{-n}}$$
Take a $412,500 loan at 6.35% over 30 years. The monthly rate is 0.529167%, and the formula returns $2,566.72 a month. Of the first payment, $2,182.81 is interest and only $383.91 is the monthly principal reduction. Over 360 payments you repay $924,020.02, which means $511,520.02 of total interest.
A fixed-rate borrower gets a stable payment that never moves, and an amortizing loan that is a traditional mortgage in the plainest sense: by the last payment you own the house outright.
Interest-Only Mortgage Formula and Payment Reset
An interest only loan has two phases. During the first phase the payment is simply the balance times the monthly rate:
$$M_{IO} = P \times i$$
Using the same $412,500 at a quoted 6.85% with a 10-year interest-only window, that works out to $2,354.69 a month, which is $212.03 less than the fixed payment. Because no principal is repaid, the balance on day one of year 11 is still $412,500.
After the initial period the loan becomes fully amortizing over the remaining 240 months, and the same formula applies with \(n = 240\):
The payments will increase by $806.39 a month, a jump of 34.2%, and that is $594.35 more than the fixed-rate borrower has been paying. Across the full 30 years you make $1,041,220.09 in total payments, so the total cost in interest is $628,720.09, which is $117,200.07 above the fixed plan.
The I-O ARM Catch
Many lenders offer the I-O ARM, an adjustable-rate mortgage in which the rate itself can change after a fixed introductory stretch. When rates reset higher, the new payment can climb well beyond the figure above, a risk this calculator holds constant by assuming one rate throughout. Treat the result as a floor, not a ceiling, whenever your offer carries a variable rate.
Measure
Fixed-rate plan
Interest-only plan
Interest rate
6.35%
6.85%
Loan term
30 years
10 years interest-only, then 20 years
Monthly payment, years 1-10
$2,566.72
$2,354.69
Monthly payment, years 11-30
$2,566.72
$3,161.07
Balance after 10 years
$348,375.66
$412,500.00
Total interest
$511,520.02
$628,720.09
Total repaid on the interest-only loan builds from $412,500 borrowed to $1,041,220.
Fixed Rate vs Interest Only: Which Plan Fits Which Buyer
Neither structure is better in the abstract. A fixed-rate loan trades a higher payment now for certainty and ownership; an interest-only structure trades ownership for room in the monthly budget. The right pick depends on how long you will hold the loan and what you do with the cash.
Who Uses an Interest Only Loan
Real estate investors who want to maximize cash flow while they renovate and resell.
Short-term homeowners who plan to sell or refinance before the payment resets.
Owners of a rental property whose rent covers the lower payment comfortably.
First-time buyers in a hot housing market who expect to refinance or sell before the window closes, and investor buyers chasing quick resale gains.
Borrowers with irregular income, such as commissions, who expect bonuses and want to make extra payments only when cash arrives.
Who Should Stay With a Traditional Loan
Most homebuyers who intend to stay put are better served by a traditional loan or a standard loan with level payments. Over 90% of owner-occupied home loans are still structured this way because the payment is predictable and every month builds a little more ownership. If your budget is already tight at the fixed payment, an interest-only plan will not improve your affordability; it only delays the squeeze. The lower early loan payments are a timing difference, and the amortizing payments that follow must still be met from the same income.
Testing a $268,900 Offer With the Fixed vs Interest-Only Loan Comparison
A buyer with a $74,400 household income has an accepted offer and a lender quoting two loans on $268,900: a 30-year fixed at 6.10%, and a 7-year interest-only structure at 6.55%. The interest-only quote looks friendlier on the worksheet, so they enter both into the calculator before signing anything.
The fixed side returns $1,629.52 a month. The interest-only side returns $1,467.75 for 84 months, a saving of $161.77 a month, about $13,589 across the window. Then the calculator shows the line that matters: after year seven, with 276 months left, the payment becomes $1,888.01, which is $420.26 above the interest-only payment and $258.49 above the fixed one.
Total interest on the fixed loan: $317,727.19.
Total interest on the interest-only loan: $375,480.18, or $57,752.99 more.
Balance after seven years on the interest-only loan: still $268,900.00.
Next comes a check against a named yardstick, the 28% front-end ratio many lenders use as a ceiling for housing cost against gross income. At $74,400 a year, 28% allows $1,736 a month. The fixed payment of $1,629.52 fits under that line, and the $1,467.75 introductory payment does too, but the post-reset $1,888.01 breaks it; it would need an income of about $80,915. Unless a raise is already scheduled, the cheaper start is only a postponed problem.
The decision follows from the number: the buyer takes the fixed loan, then reruns the comparison once with a 10% larger down payment to see how much headroom remains below the ratio.
Pros and Cons of an Interest-Only Mortgage
Weigh the pros and cons against your own plans rather than the headline payment.
Advantages
A lower monthly payment in the early years, which helps you afford a bigger home or free up cash for repairs.
Flexibility: you may send extra principal in good months and fall back to the minimum in lean ones.
Money not spent on principal can go toward investing only if you expect returns above your loan rate; the $212.03 monthly saving in the example would have to earn more than the 6.85% you pay to justify the reset.
Risks
You do not build equity from payments, so you rely on appreciation and a healthy housing market to gain ownership.
If the home price falls, you may owe more than the property is worth with nothing paid down.
The payment jumps once the interest-only window ends.
Higher total interest, since the balance stays at its peak for longer.
What Lenders Look For Before You Qualify for Either Loan
An interest-only mortgage is rarely backed by FHA and similar government programs, so the lender carries more risk and applies stricter rules. To qualify for one you typically need strong credit scores, a low debt-to-income ratio, solid savings and a sizeable down payment. Lenders also size your income against the post-reset payment, not the introductory one, so run the comparison and test the higher payment against your debt-to-income limit before you apply.
Costs Outside the Loan Payment
Remember that your monthly outlay includes more than principal and interest. Property taxes and homeowners insurance are commonly collected through an escrow account, and the calculator leaves them out, and they apply equally to both plans, so they shift your budget but not the comparison between the two loan types.
Total Interest and Total Payments Compared
The bottom line is the total interest you pay across the life of the loan. In our example, the interest-only borrower spends $282,562.50 on interest during the first ten years, then another $346,157.59 on interest rates applied to the amortizing phase. The fixed-rate borrower pays less in total because every payment retires part of the balance, and a smaller balance accrues less interest.
Payment Shock After the Initial Period
The stretch of time before reset and the rate you are quoted both drive the new payment. A longer window means fewer years left to repay, so the amortizing payment is higher. The grid below shows the payment after reset on the same $412,500 loan over a 30-year total term, at three quoted rates.
Payment after reset for three rates and three interest-only windows; the outlined cell is the worked example.
Interest-only rate
5-year window
7-year window
10-year window
6.35%
$2,747
$2,846
$3,039
6.85%
$2,876
$2,972
$3,161
7.35%
$3,008
$3,102
$3,285
Refinance or Pay Down Before the Reset
Many borrowers plan to refinance into a fixed rate before the window closes. That only works if you still qualify and today's mortgage rates are no worse than your loan, so a prudent plan also tests the case where you cannot refinance. Sending extra principal during the interest-only years shrinks the post-reset principal balance, which softens the jump.
How to Read Your Fixed Rate vs Interest-Only Results
Look at three numbers in order, starting with your current mortgage payment against the alternative. First, the monthly payment gap between the plans tells you the monthly saving. Second, the payment after the interest-only period tells you whether you can survive the reset. Third, the difference in total interest is the price of the saving.
In the example, the saving is $212.03 a month, or $2,544 a year, for ten years, while the cost is $117,200.07 more in total interest. Use the calculator to compare several scenarios, adjusting the rate, loan term, loan amount or interest-only period one at a time. A tool like this works with the stated interest rate and ignores taxes and fees, so confirm final numbers with the lender before you borrow.
The formula takes the form \(M = P \times i\) before reset1, and the amortizing version afterward.
See how the Fixed Rate Mortgage vs. Interest-Only Mortgage Calculator works: change the inputs and the net worth lead updates instantly. Enter your own numbers in the calculator above.
1 Assumes a constant rate and monthly compounding, with no balloon loans or prepayment.
Common Questions About Choosing Between the Two Loans
Is an interest-only payment ever lower than a fixed payment at the same rate?
Yes, always in the early years, because it contains no principal. On the example balance at 6.35%, interest alone is $2,182.81, roughly $384 below the fixed payment, but the savings reverse once the reset arrives. A home loan structured this way also leaves the balance untouched.
Can I switch later?
Often yes, through a refinance or recast, though neither is guaranteed. Equity, credit and market rate levels at that time decide the finance terms offered.
Fixed Rate Mortgage vs. Interest-Only Mortgage Calculator questions
What is the difference between a fixed-rate and an interest-only mortgage?
A fixed-rate loan has the same payment every period and repays principal from the first payment. An interest-only loan charges only interest for a set period, so the balance stays the same until the interest-only period ends and a higher payment begins.
Why does the payment rise after the interest-only period?
No principal was repaid during that period, so the full original balance must be paid off over fewer remaining years. The shorter repayment window and the larger balance push the amortizing payment above the interest-only payment.
Is an interest-only mortgage cheaper overall?
Usually not. You pay less each period at first, but the balance stays higher for longer, so total interest is generally higher than on a fixed-rate loan. The calculator's Which One Is Cheaper? result shows the answer for your numbers.
Who might choose an interest-only loan?
Short-term owners who plan to sell or refinance before the reset, real estate investors managing cash flow, and borrowers expecting a large income rise. Anyone relying on a refinance should also test the case where they cannot refinance.
Can I make extra principal payments on an interest-only loan?
Many lenders allow it. Extra principal reduces the balance, which lowers interest and softens the payment increase when the interest-only period ends. Check your loan terms for prepayment rules.
What does this calculator leave out?
It assumes one interest rate for the whole loan and ignores property taxes, homeowners insurance and mortgage insurance. If your loan is an adjustable-rate mortgage, payments can change when rates reset.
How much income do I need to qualify for each loan?
Lenders compare your housing payment to your income, often using a ratio around 28% of gross monthly income for housing. Test the payment after the interest-only period, because many lenders qualify you on that higher figure.