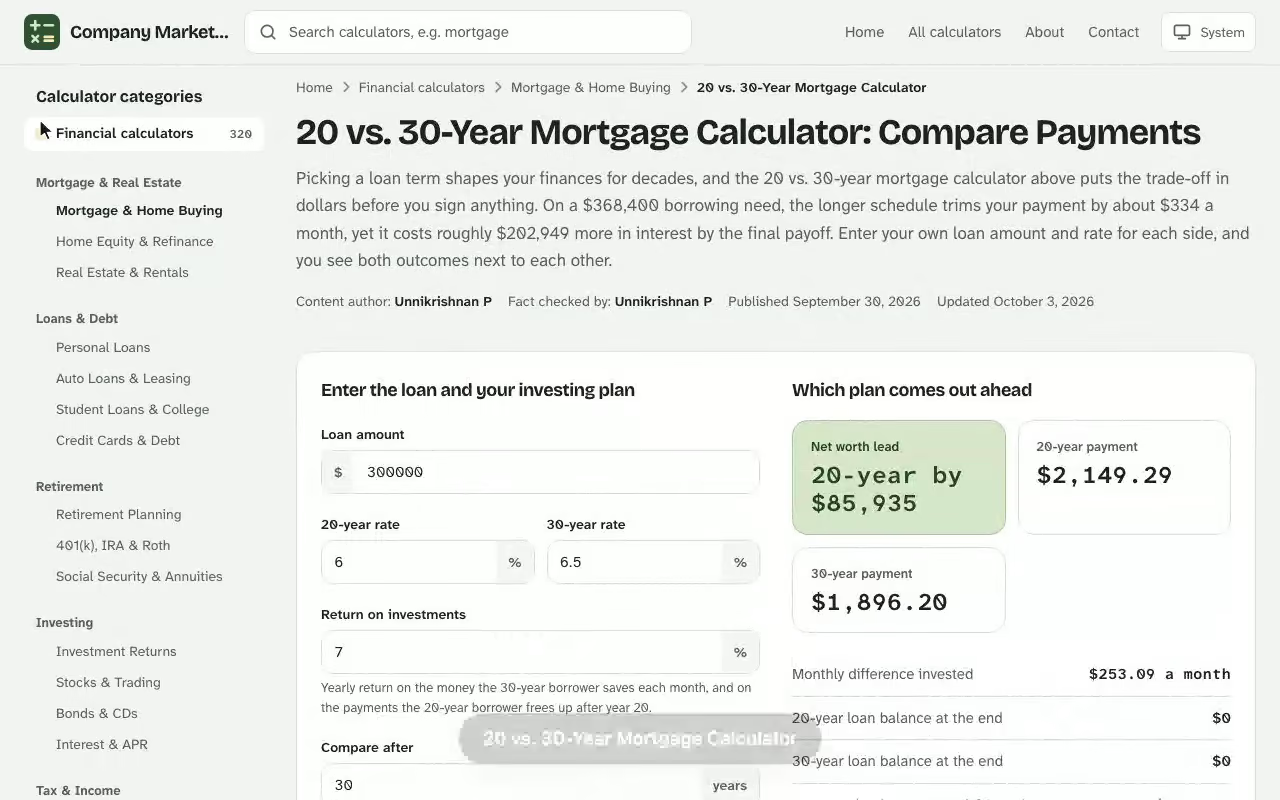
20 vs. 30-Year Mortgage Calculator. Picking a loan term shapes your finances for decades, and the 20 vs. 30-year mortgage calculator above puts the trade-off in dollars before you sign anything. On a $368,400 borrowing need, the longer schedule trims your payment by about $334 a month, yet it costs roughly $202,949 more in interest by the final payoff. Enter your own loan amount and rate for each side, and you see both outcomes next to each other. Pair this with the free amortization calculator for a fuller picture before you make a decision.
Which plan comes out ahead
Net worth lead
–
20-year payment
–
30-year payment
–
Monthly difference invested–
20-year loan balance at the end–
30-year loan balance at the end–
20-year plan investments (after tax)–
30-year plan investments (after tax)–
20-year plan: investments minus loan–
30-year plan: investments minus loan–
Total interest, full 20-year loan–
Total interest, full 30-year loan–
Return where both plans finish level–
–
Both households spend the same each month: the 20-year payment for the first 20 years, then the 30-year payment. Results are at the end of year –.
Net worth year by year
Loan balances and invested savings for each plan. The last column shows which plan is ahead and by how much.
Year
20-yr balance
20-yr investments
30-yr balance
30-yr investments
Ahead
Results are estimates for educational purposes and are not financial, tax or legal advice.
How the 20 vs. 30-Year Mortgage Calculator Compares Fixed-Rate Mortgages
Most buyers choose a fixed-rate mortgage because the rate, and therefore the principal and interest payment, never changes. A fixed-rate mortgage with a 240-month schedule and one with a 360-month schedule can start from the same price and still cost very different amounts, because time is the largest cost lever you control. The tool lets you compare 20 & 30 year fixed-rate mortgages line by line, so you can see the monthly payments, the total interest and the payoff date without building a spreadsheet. Try the biweekly mortgage calculator online to run your own numbers — everything is calculated in your browser and nothing you enter is stored or sent anywhere.
Lenders usually price shorter schedules lower, so the two sides rarely share a rate. Rather than assuming they match, enter each quote separately and let the numbers show whether a 20 or 30 year commitment fits your plans.
Inputs you enter for each loan
Loan amount: the price of the house minus your down payment, so a larger down payment shrinks both sides at once.
Interest rate: the quoted annual rate for each schedule, which is often a fraction of a point lower on the shorter one.
Loan term: 20 years on one side and 30 on the other by default, though you can change either to test other lengths.
Property taxes, homeowners insurance and HOA dues: optional monthly extras that are identical on both sides, so they raise the totals without changing the gap.
Private mortgage insurance (PMI): an add-on if you borrow more than 80% of the home's value.
Reading the results: monthly payment and total interest
The first number to read is the monthly payment, because it tells you whether the loan fits your budget. The second is total interest, which is everything you hand the lender above the amount you borrowed. Read both together: a payment that looks comfortable can hide a six-figure interest bill, and a cheap total can hide a payment you cannot sustain.
Worked Example: A $368,400 Home Loan at a 20-Year and a 30-Year Mortgage Term
Take a loan amount of $368,400. Suppose your lender quotes 6.250% for a 20-year schedule and 6.625% for a 30 year FRM, which is a typical gap of three-eighths of a point. The table shows what the calculator returns for the principal and interest portion. The free balloon loan calculator uses the same plain-English approach, so you can compare results side by side.
Measure
20-year fixed
30-year fixed
Interest rate
6.250%
6.625%
Monthly principal and interest
$2,692.74
$2,358.91
Total of all payments
$646,257
$849,206
Total interest
$277,857
$480,806
Interest expense in month one
$1,918.75
$2,033.88
Principal paid in month one
$773.99
$325.03
The shorter option asks for $333.83 more each month and saves $202,949 in interest. In the first month, more than twice as much of your payment reduces the principal on the 20-year loan, which is the early sign of faster progress.
Total cost of the $368,400 example: $277,857 of interest over 20 years versus $480,806 over 30 years.
The payment formula behind the numbers
Every fixed-rate payment comes from the same equation, where \(P\) is the loan amount, \(r\) is the monthly interest rate (the annual rate divided by 12) and \(n\) is the number of monthly payments:
$$M = P \times \frac{r(1+r)^{n}}{(1+r)^{n}-1}$$
Total interest is simply \(M \times n - P\). Because \(n\) appears in the exponent, stretching the schedule from 240 to 360 payments lowers \(M\) but multiplies the number of months in which interest accrues.
Interest over the life of the loan
Interest over the life of the loan is the gap that matters most to long-term planners. In this example the extra 120 months add almost $203,000 of cost, a sum larger than half the amount you originally borrowed. An amortization schedule shows how it happens: early payments are mostly interest, and only later does amortization shift the balance toward principal.
Monthly principal and interest on $368,400 by rate and loan term.
Pros and Cons of a 30 Year FRM and a Shorter Loan Term
Neither schedule is universally better. Each one is the right tool for a different borrower, and the calculator helps you see which description fits you.
Advantages of the longer schedule
A lower monthly payment makes it easier to qualify for a larger loan and leaves room in your budget for repairs and emergencies.
If a bonus or inheritance arrives, you can send extra payments toward the principal and still keep the lower required payment.
The monthly payments stay the same if rates climb, and you can refinance if rates fall.
You can direct the monthly savings into investments or a tax-advantaged retirement account, if you expect those to outperform your mortgage rate.
Advantages of the shorter loan term
You pay less in interest, both because the rate is lower and because the balance disappears sooner.
You build equity faster, which helps if you plan to sell or refinance within ten years.
You pay off the property twenty years from the start, a useful goal if you hope to retire without a house payment.
Unlike an adjustable-rate loan, the rate cannot reset upward, so your payment is predictable for the whole schedule.
The trade-offs on each side
The longer schedule's weakness is cost: you commit to paying the lender for another decade, and the interest deduction on the first $750,000 of debt offsets only a portion of that expense. The shorter schedule's weakness is rigidity. A bigger required payment narrows your flexibility if your income drops or a job ends, and the money you send to the house is no longer available for other goals. In the worked example, that rigidity is the extra $333.83 a month on the 20-year side, while the flexibility of the 30-year side is paid for with $202,949 of added interest. Enter your own figures to see where your numbers land.
How the Loan Term Changes Home Equity and Loan Balance
Your home equity is the share of the property you own outright, and the mortgage term controls how fast it grows. The table tracks the remaining loan balance and the equity built through payments alone, so appreciation is left out and any price growth would sit on top.
After
Loan balance, 20-year
Loan balance, 30-year
Equity from payments, before appreciation (20 / 30)
5 years
$314,050
$345,355
$54,350 / $23,045
10 years
$239,823
$313,288
$128,577 / $55,112
15 years
$138,449
$268,670
$229,951 / $99,730
20 years
$0
$206,586
$368,400 / $161,814
Remaining balance at each checkpoint: the 20-year loan reaches $0 while $206,586 is still owed on the 30-year loan.
Look at year ten. Homeowners relocate or refinance every decade or so, and at that point the 20-year borrower holds $73,465 more equity than the 30-year borrower. The gap between the two columns is the real reward for the higher payment.
Checking a 20 or 30 Year Home Loan Against a 28% Housing Ratio
Marguerite earns $9,400 a month before tax and has a $291,750 balance to finance. Her lender's guideline caps housing costs at 28% of gross income, which works out to $2,632 a month, so she opens the comparison tool with that ceiling in mind. Taxes and insurance are $612 a month on either schedule.
She enters 6.500% for 20 years on the left and 6.875% for 30 years on the right. The result shows the monthly payment comparison she needed: $2,175.21 for the 20-year loan and $1,916.59 for the 30-year loan. Adding the $612 gives $2,787.21 and $2,528.59, or 29.7% and 26.9% of her income. Only the longer loan clears the 28% line, even though it would cost $398,222 in interest against $230,300.
Before accepting the longer loan, she reruns the 20-year side with one input changed. Moving $30,000 of savings into the down payment drops the balance to $261,750, and the payment falls to $1,951.54. With taxes and insurance that is $2,563.54 a month, 27.3% of her income and under the lender's ceiling. Interest on this smaller loan comes to $206,619, which is $191,603 less than the 30-year path she started with.
Her decision is concrete: she brings the larger down payment to her lender and asks for the 20-year quote, keeping the 30-year figures as a fallback if her pre-approval comes in below the quoted rate.
Costs Beyond Principal and Interest: PMI, Property Taxes and HOA Dues
The calculator's principal and interest result is only the core of what you pay each month. Home buyers also owe several recurring costs that are the same under either schedule, though they change how heavy the higher payment feels.
Property taxes: set by local government and usually billed as a percentage of the home's value.
Homeowners insurance: required by every lender and priced by size, age and location.
HOA dues: a monthly fee if the property belongs to a homeowners association.
PMI: a charge if your down payment is under 20%, which ends once the loan balance falls below 80% of the value.
Closing costs: a one-time bill of roughly 2% to 5% of the loan amount.
Add these to both sides before you decide. A house that seems affordable on a 30-year payment of $2,358.91 can feel stretched once taxes and insurance join it, and the 20-year option may then be out of reach.
Qualifying for a Home Loan Under Either Term: Down Payment, Lender Rules and Loan Limits
Whichever term you favor, your lender decides whether you can have it. Your down payment sets the loan amount you type into the calculator, and a payment of 20% avoids PMI and usually earns a better quote, and about a third of buyers who use financing reach that mark. If you cannot, FHA loans, VA loans and USDA loans offer lower down payment routes.
See how the 20 vs. 30-Year Mortgage Calculator works: change the inputs and the net worth lead updates instantly. Enter your own numbers in the calculator above.
It also pays to get pre-approved before house hunting, since a pre-approval confirms how much you can borrow at which payment. Ask for a quote on each schedule and enter each quoted rate as a separate input, because the shorter term usually prices lower; the weekly Freddie Mac survey is a handy check that each quote is realistic. Many banks let you prequalify online in a few minutes. When you compare quotes, look at the APR as well as the interest rate, because APR folds in fees and shows the real cost of each offer.
The conforming loan limit for a single-unit home in most of the country is $832,750 for 2026. Loans above it are classified as jumbo loans, and they come with stricter underwriting and sometimes different rates, so they may price the two terms differently. Check the limit for your county before choosing a purchase price, then enter each quoted rate into the comparison.
Choosing Between a 20 or 30 Year Mortgage Term
Use the calculator's results to answer three questions: can the higher payment fit comfortably in your budget, would the freed-up cash earn more elsewhere, and how steady is your income?
Run both schedules with real quotes from at least two lenders.
Subtract the shorter loan's payment from the longer loan's. In the example above, that difference is $333.83 a month.
Decide what that money would do. Invested at 5% a year for twenty years, $333.83 a month grows to about $137,217, which is well short of the $202,949 of extra interest the longer loan produces.
Test your stability. If your employment is secure and your debt is low, the shorter schedule's rigidity is less risky.
The calculation above ignores taxes on investment gains and the mortgage interest deduction, both of which could narrow the gap. Another route is a hybrid: take the longer schedule for the safety of a lower required payment, then make extra payments whenever your cash flow allows. You keep the flexibility, and you shorten the payoff on your own terms, although you will still pay the higher rate on the longer loan.
Uncertainty about the future is the real tiebreaker. A stable salary and a goal of owning your real estate outright favor the shorter loan, while a variable income, a young family or other priorities for your savings favor the longer one. Run the numbers again each time your situation changes, and revisit the choice when mortgage rates move enough to justify a refinance.
20 vs. 30-Year Mortgage Calculator questions
Is a 20-year or 30-year mortgage better?
Neither is better for everyone. A 30-year loan gives you a lower required payment and more room in your monthly budget, while a 20-year loan costs far less interest overall and builds equity faster. Enter a real quote for each loan above to see the exact trade-off for your numbers.
How much interest do I save with a 20-year mortgage?
The savings come from two sources: the lender usually charges a lower rate on the shorter term, and you stop paying interest ten years sooner. The Total Interest Expense result shows the gap in dollars for the two loans you enter.
Why are the rates different for each loan?
Lenders usually price shorter fixed-rate terms a fraction of a percentage point below longer ones, because they carry the risk for less time. Enter each loan's own APR so the comparison reflects the quotes you actually received.
When do I have to pay private mortgage insurance (PMI)?
PMI is typically required when your down payment is under 20% of the home price on a conventional loan. This calculator charges PMI only when that condition is met, and you can set the rate for each loan.
What is included in the all-in monthly payment?
It combines principal and interest with monthly property taxes, homeowners insurance, PMI and any HOA fees. The principal and interest result alone is the part that changes with the loan term.
Should I include closing costs in the loan?
Use the closing costs field only if the lender lets you finance them. Financed costs raise the amount borrowed and the interest you pay, so compare the result with and without them.
How fast do I build equity on each term?
Much faster on the shorter loan, because a larger share of every payment goes to principal. The amortization table lists the balance at the end of each year for both loans so you can compare them side by side.
Can I pay off a 30-year mortgage early?
Most conventional loans allow extra payments toward principal without a penalty, but check your loan terms. Paying extra on the longer loan shortens the payoff while keeping the lower required payment as a safety net.