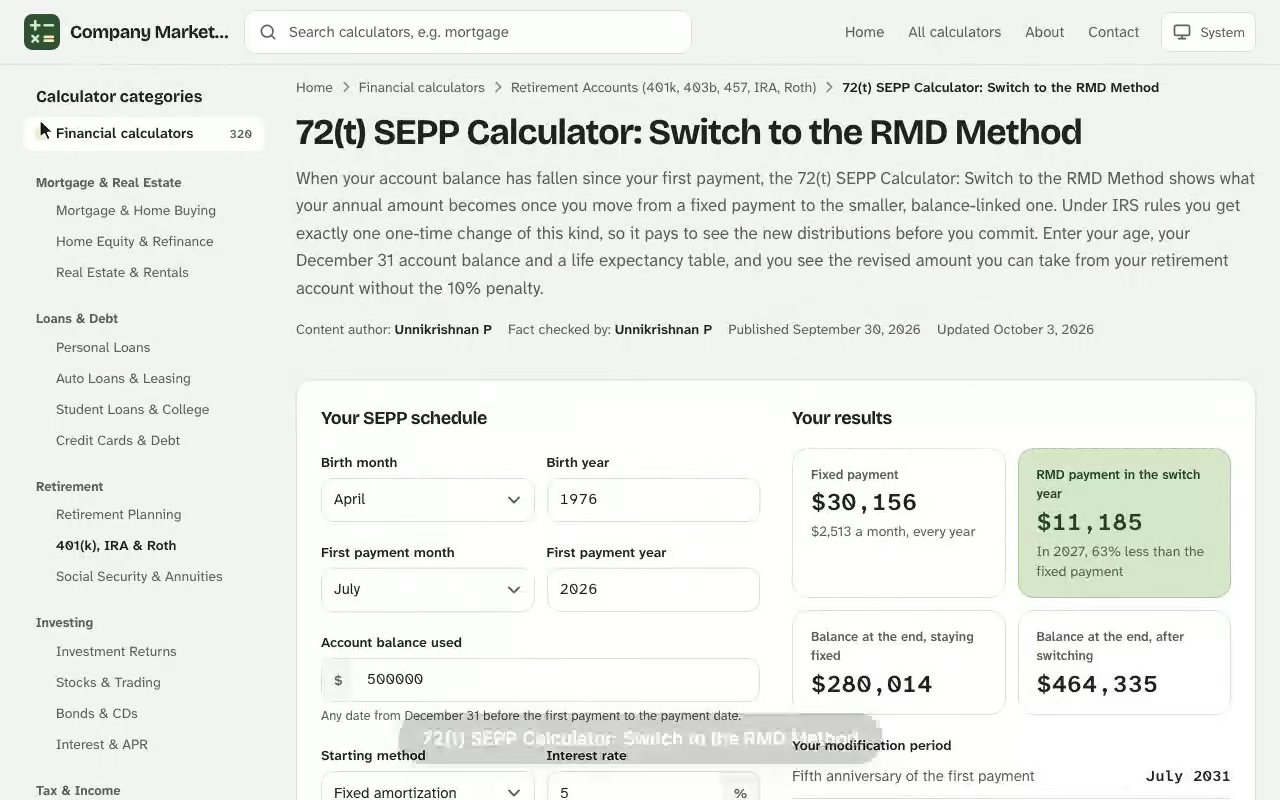
72(t) SEPP Calculator: Switch to the RMD Method. When your account balance has fallen since your first payment, the 72(t) SEPP Calculator: Switch to the RMD Method shows what your annual amount becomes once you move from a fixed payment to the smaller, balance-linked one. Under IRS rules you get exactly one one-time change of this kind, so it pays to see the new distributions before you commit. Enter your age, your December 31 account balance and a life expectancy table, and you see the revised amount you can take from your retirement account without the 10% penalty. The roth ira calculator is free to use with no sign-up, and works on desktop and mobile.
Your results
Fixed payment
–
RMD payment in the switch year
–
Balance at the end, staying fixed
–
Balance at the end, after switching
–
Your modification period
Fifth anniversary of the first payment–
You reach 59½–
Schedule must hold until–
Annual payments required–
Total paid, staying fixed–
Total paid, after switching–
Allowed without the 10% coming back
One switch from fixed amortization or annuitization to the RMD method, for that year and every year after.
The account running out because of the method you follow.
Death or disability.
Counts as a change before the period ends
Taking more or less than the schedule, or skipping a year.
Adding money to the account, other than investment growth.
Moving part of the balance to another plan or IRA, or rolling a payment over.
Switching back from the RMD method, or switching a second time.
Staying fixed vs switching to RMD
One payment per calendar year, taken at the end of the year after that year’s return, for every year the schedule must hold.
Payment
Year
Age
Fixed payment
Balance, fixed
Payment with switch
Balance, switch
Results are estimates for educational purposes and are not financial, tax or legal advice.
Using the 72(t) SEPP Calculator: Switch to the RMD Method Step by Step
A series of substantially equal periodic payments (a SoSEPP) lets you take money from an IRA or a workplace retirement account before age 59½ without the early distribution penalty. Most people open a SEPP plan with the fixed amortization method or the fixed annuitization method, because both produce larger payments. The switch tool starts from the opposite situation: your SoSEPP already exists, and you want to know what it looks like under the new method. Because the SoSEPP is binding, run the switch and compare the new annual amount with your yearly spending before you act. Next, open the roth plan contributions calculator and enter your own details to see an estimate in seconds.
Inputs You Enter for the Switch
The form asks for the same few facts the IRS asks you to document, and each one changes the result:
Your age in the calendar year of the new payment, because the factor is based on your attained age.
Account balance as of December 31 of the prior year, the last valuation date before the payment is redetermined.
Life expectancy table: uniform lifetime, single life or joint life expectancy.
Beneficiary age, needed only for the joint table.
Payment schedule: annual, monthly or quarterly installments of the annual amount.
Account eligibility: only an eligible IRA or employer plan account can carry the SoSEPP.
What the Results Show
Press the calculate button and you get the new annual amount, the monthly equivalent, and the percentage of your balance it represents. Your old fixed payment goes next to it so you can see the size of the cut. Because the division uses a life expectancy factor rather than amortizing at an interest rate, the number is almost always the lowest payment of the three IRS-approved methods. That is the point of the switch: a lower withdrawal is easier for a shrunken account to sustain.
How the RMD Method Sets Your Annual Amount
The required minimum distribution method is the simplest of the three. It uses no interest rate at all, which makes it the only method whose payment changes as your account moves. The formula is: If you want to see how the figures change, the roth ira conversion with distributions calculator gives you an instant result you can adjust as you go.
$$\text{Annual amount} = \frac{\text{Account balance on December 31}}{\text{Life expectancy factor for your attained age}}$$
Each year you rerun the division with the new prior-year balance and the factor for your new age. When markets rise, your payment rises; when your balance falls, so does the withdrawal. Providers such as Fidelity note that this method suits a smaller bridge income with more retirement savings left to grow tax-deferred, which is the trade the switch makes. Because you recompute the amount annually, the SoSEPP follows your investment results instead of ignoring them.
RMD method payment by account balance and age using single life table factors.
Choosing a Life Expectancy Table
Whether you take distributions monthly or once a year, the table decides the size of each one. Notice 2022-6 allows three tables for the RMD method, and your choice moves the answer by a wide margin.
Life expectancy table
Based on
Effect on your payment
Uniform lifetime table
Your age only, with a hypothetical younger beneficiary
Larger factor, so a smaller payment
Single life table
Your own single life expectancy
Smaller factor, so a larger payment
Joint life expectancy
You and your named beneficiary age
Largest factor when your beneficiary is much younger
Whichever table you pick, you must keep it for the life of the plan. Switching tables later counts as a modification.
How 72(t)/SEPP Payments Work Year to Year
The first annual amount is paid from your balance on the last valuation date before the first distribution. After that, each January you divide the December 31 balance by the factor for your attained age. Your account owner statements make that figure easy to find. You may split the annual amount into monthly or quarterly installments, but the total for the year has to equal the computed amount.
Worked Example: Moving a Fixed Amortization Plan to the RMD Method
Consider an IRA owner who starts a SoSEPP at age 54 with a balance of $538,600 and chooses the fixed amortization method at a 5.00% rate over a single life expectancy of 32.5 years. The amortization factor is 15.9038, so the fixed annual amount is $538,600 ÷ 15.9038 = $33,866. The same balance under the RMD method would have paid $16,572, but this owner wanted the larger payment.
After two years of fixed payments and a market decline, the December 31 balance sits at $431,900 and the owner turns 56. The fixed payment now takes 7.84% of the account every year. Switching with the single life table factor of 30.6 gives:
$$\frac{\$431{,}900}{30.6} = \$14{,}114$$
That is 3.27% of the balance and $19,752 less per year than the fixed amount. The table compares the next four years, assuming a 4% annual return on the remaining balance, which is an illustration and not a forecast.
Age
Balance at start of year
Life expectancy factor
RMD method payment
Fixed amortization payment
56
$431,900
30.6
$14,114
$33,866
57
$434,497
29.8
$14,580
$33,866
58
$436,713
28.9
$15,111
$33,866
59
$438,466
28.0
$15,660
$33,866
Over those four years the switched plan pays out $59,465 in total, against $135,464 for the fixed plan. Left on the original schedule, the balance would shrink to about $355,699 by the end of age 59, while the switched account would hold about $439,718.
Fixed amortization versus the RMD method, ages 56 to 59.
Mechanics of the Switch Year
In the year you change, the IRS expects the RMD calculation to behave as if you had used it from the start of that year. You take the prior December 31 balance, find the factor for the age you attain in the current calendar year, and divide. If the owner above had waited until 57, the same division would have used $434,497 and 29.8. Pick the year deliberately, because the factor shrinks and the balance moves every twelve months. Tell your custodian in writing which method and table you are adopting, and ask them to code the payments accordingly.
What the Lower Payment Means for Cash Flow
The RMD-method result puts the new annual amount next to the old one: a drop from $33,866 to $14,114 is a cut of roughly 58%, Match it against your fixed expenses before you submit the paperwork. Because distributions are fixed by the formula, you cannot top them up in a lean month. Dividing the new annual amount by twelve gives $1,176 per month, and by four gives $3,529 per quarter. If that is less than your fixed expenses, you may need a second income source because you cannot add a second withdrawal from the same account without a modification. This is the trade the new method makes: lower payments now in exchange for a balance that is less likely to run out before age 59½ and well beyond.
SEPP Plan Rules to Keep When You Switch Methods
A SEPP plan is only penalty-free while you obey its rules. The calculator gives you the number; keeping the plan intact is on you.
The Five Years and Age 59½ Requirement
Payments must continue until the later of five years after your first distribution or the date you reach age 59½. Starting at 54, the owner in the example above must keep taking payments until the 59½ date, which falls after the fifth anniversary. The clock does not stop when you switch methods.
A SEPP plan runs until the later of five years or age 59½.
The Modification Rule and the Recapture Tax
Any modification of the SoSEPP before that date, such as skipping a payment, taking extra money or adding contributions, triggers the recapture tax. The 10% additional tax then applies retroactively to every payment since the first distribution, plus interest. That second additional tax is why one wrong payment can cost more than the whole plan saved. Only death or disability, or a distribution to a qualified public safety employee, lets you change the SoSEPP without that result.
What the One-Time Change Allows
The single exception that most people use is the one-time change from fixed amortization or annuitization to the RMD method, first allowed by Revenue Ruling 2002-62 and carried forward by Notice 2022-6. Once made, the change is permanent for the SoSEPP. You cannot move back, and you cannot move from RMD to another method. If the account is depleted, the payments end without a penalty, which is why some owners choose the RMD method after heavy losses.
Accounts Covered by 72(t)/SEPP and Separation From Service
The switch stays on the same single account, since a SoSEPP never combines balances and 72(t)/SEPP treats each account separately. If that account came from 401(k)s or another employer retirement plan, you were separated from service before the first payment; IRA owners had no such condition.
Running the 72(t) Calculator Before Changing a SoSEPP
It is the second week of January, and a 57-year-old landscaper has the December 31 statement open. Two years ago a fixed amortization SoSEPP started paying $38,415 a year. A failed equipment venture inside the same IRA has since dragged the balance down to $344,720, so each payment now removes 11.1% of what is left.
See how the 72(t) SEPP Calculator: Switch to the RMD Method works: change the inputs and the rmd payment in the switch year updates instantly. Enter your own numbers in the calculator above.
Before calling the custodian, the landscaper enters the facts into the switch tool: age 57, balance $344,720, single life table. The tool pulls the factor of 29.8 from the Notice 2022-6 table and divides:
$$\frac{\$344{,}720}{29.8} = \$11{,}568$$
The result is $11,568 for the year, or $964 a month, which is 3.36% of the balance. Set beside the old $38,415, the shortfall is $26,847 a year, or $2,237 a month. The old schedule is drawing 11.1% of the account, more than three times the 3.36% the new method allows, and the landscaper can see why the balance keeps shrinking.
Two decisions follow from that number. First, the landscaper asks the custodian to re-code the account to the RMD method before the first payment of the year, because the one-time change cannot be undone and the paperwork must say so. Second, the landscaper sets aside $2,237 a month from taxable savings to replace the missing income, since adding a second withdrawal from the IRA would be a modification and bring the recapture tax. With the plan not ending until the 59½ date, about two and a half years away, the lower payment protects the account balance for the remaining stretch.
Comparing the Fixed Amortization, Fixed Annuitization and RMD Methods
All three are IRS-approved methods, and each divides your balance in a different way. Here is how they stack up.
Method
Uses an interest rate
Payment changes
Typical size
Required minimum distribution
No
Yes, every year
Lowest
Fixed annuitization
Yes, with an annuity factor from a mortality table
No
Middle
Fixed amortization
Yes
No
Highest
Fixed Amortization Method and Fixed Annuitization Method
The fixed amortization method spreads your account balance over your life expectancy as if it were a loan, which is why amortizing produces the biggest check. The fixed annuitization method divides the balance by an annuity factor, the present value of $1 per year for life based on a mortality table and your chosen rate. Both lock in fixed payments for the life of the plan, apart from the switch.
Interest Rate and Federal Mid-Term Rate Limits
For the two fixed methods you choose a reasonable interest rate. The ceiling is the greater of 5% or 120% of the federal mid-term rate for either of the two months before your first payment. A lower interest rate gives a smaller payment. The federal mid-term rate follows Treasury yields, so it moves from month to month, and your custodian can show you the published figure. The switch removes the rate input entirely, which is one reason people who dislike guessing at rates prefer the RMD method.
Taxes on Your SoSEPP Payments After the Switch
The SEPP exception removes the premature distribution penalty, not the income tax, so a 72(t) distribution is still taxable. At a 22% federal bracket, the example's $14,114 annual amount would carry about $3,105 of federal income tax, before any state tax. A 72(t) distribution is taxable in the year you receive it. Every dollar of IRA distributions from a pre-tax account is taxed as ordinary income, with cost basis handled as it would be on any other withdrawal. Your SoSEPP payments are also reported on Form 1099-R with a code that shows the exception, so keep the calculator report with your tax records.
A 72(t)/(q) distribution cannot be combined with other early withdrawals from the same account during the plan, and extra withdrawals reduce the balance the SoSEPP depends on.
Plan for distributions in every year, since skipping one is a modification.
Add no new money and take no extra withdrawal; either counts as a modification.
Confirm the switch with a financial professional before you submit it, because it is permanent.
Reading Your Early Distribution Analysis Report
Most providers show an early distribution analysis as a printable report. When you read it, look for the following items before you rely on the figure:
The payment amount for the first year and whether it is stated as an annual distribution or already divided into monthly installments.
The distribution period or life expectancy factor used, and which table it came from.
The account balance and the valuation date, which must be a December 31 or the last valuation date before the first distribution.
Any assumption about growth, since a projected balance is a guess while the first-year payment is a rule.
The year the plan can end: the later of the five-year anniversary or the date you turn 59½.
If the switch result differs from the custodian's RMD-method amount by more than rounding, trust the custodian's statement and find the difference, since the custodian is the one reporting your distributions to the IRS. Rerun with a different table and note how the answer shifts, because that tells you how much room you have if your first choice does not fit your budget.
Mistakes That Break a Penalty-Free SEPP Plan After You Switch
People rarely lose a plan to the formula; they lose it to the details around it. Watch for these:
Missing a payment in the switch year. If a payment is late or short, making it up later still counts as a modification.
Switching twice. The one-time change allowed by the IRS is a single move. A second switch, or a move back to amortization, produces the recapture tax.
Using the wrong balance. The RMD method uses the prior December 31 balance, not today's balance and not the balance you hope to have.
Ignoring the end date. Stopping on the fifth anniversary when you have not yet reached 59½ is a modification, even though five years sounds like enough.
Keep a simple file of the RMD inputs for each year: the December 31 balance, the factor, the computed payment and the payment actually made. If the IRS ever asks, that file turns a complicated question into an easy answer.
Who the RMD Method Fits Best
The RMD method suits you if you want modest early retirement income, expect your balance to swing widely, or have lost ground since you began a fixed plan. If you expect wide fluctuations in the value of your account, the RMD method moves with it instead of fighting it. It is a poor fit if you need a large monthly amount to cover expenses, because the lowest payment of the three methods may fall short. Many owners run the 72t calculator once for each method and pick the one whose payment matches their spending. Pick one IRS-approved method, compare the retirement income each would give you, and then confirm withdrawals will cover your costs. Rerun the switch tool at each December 31 with the new balance and age, because small input errors compound across five or more years of distributions. Before you act, read the IRS guidance on substantially equal periodic payments and confirm the table factors for your own age.
72(t) SEPP Calculator: Switch to the RMD Method questions
Can I switch my SEPP plan to the RMD method?
Yes. The IRS allows a one-time change from the fixed amortization or fixed annuitization method to the RMD method without it counting as a modification. The change is permanent, so you cannot switch back.
Why is the RMD method payment lower?
It divides your prior December 31 balance by a life expectancy factor and uses no interest rate, which usually gives the lowest payment of the three IRS-approved methods.
How long must SEPP payments continue?
Until the later of five years after your first payment or the date you reach age 59½. Changing the series before then, other than the one-time switch, triggers the recapture tax.
What interest rate can I use?
For the fixed amortization and fixed annuitization methods, the rate may not exceed the greater of 5% or 120% of the federal mid-term rate for either of the two months before your first payment. The RMD method uses no rate.
Which life expectancy table should I choose?
Notice 2022-6 permits the uniform lifetime table, the single life table and the joint life and last survivor table. The single life table usually gives a larger payment than the uniform lifetime table. Keep the same table for the life of the plan.
Does the SEPP exception remove income tax?
No. The exception removes the 10% additional tax on early distributions, but your payments are still taxed as ordinary income.
Can I take extra money from the account during the plan?
No. Additional withdrawals or contributions count as a modification and can trigger the recapture tax, so use a separate account for other needs.