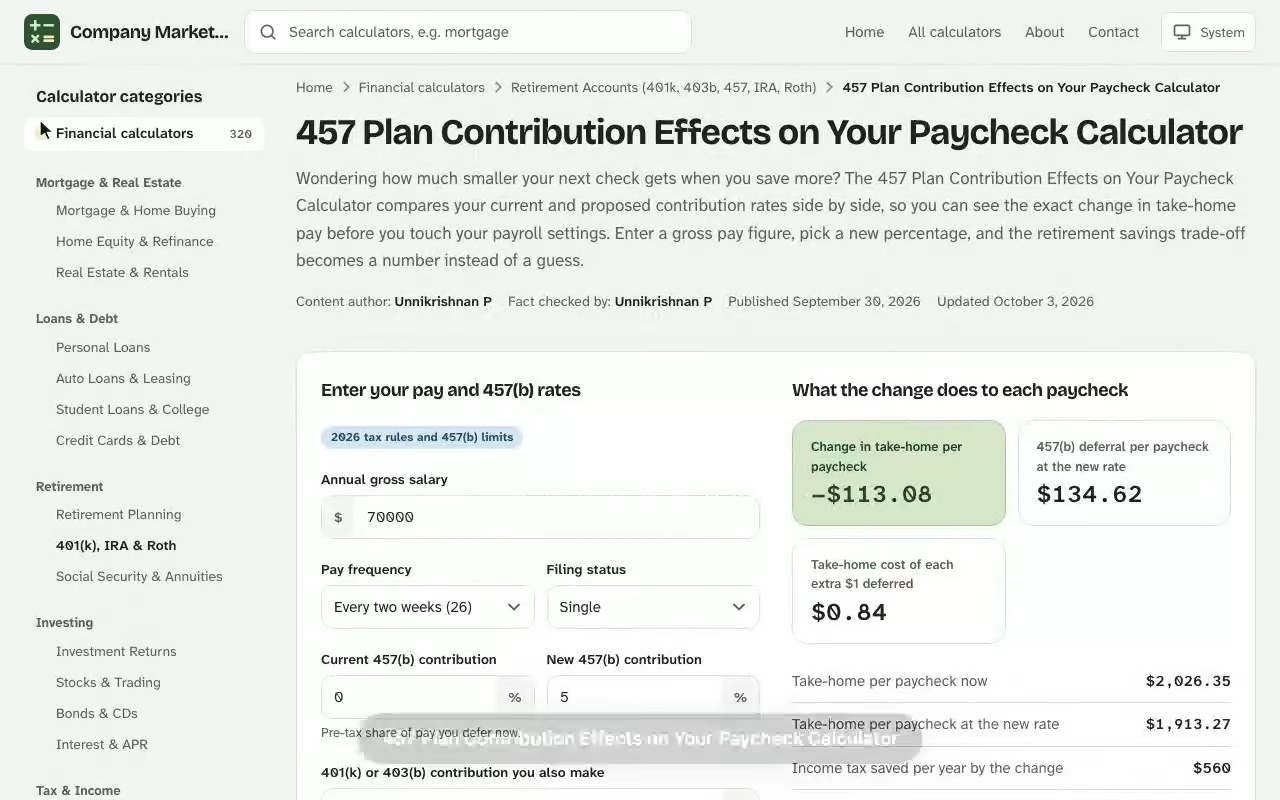
457 Plan Contribution Effects on Your Paycheck Calculator
457 Plan Contribution Effects on Your Paycheck Calculator. Wondering how much smaller your next check gets when you save more? The 457 Plan Contribution Effects on Your Paycheck Calculator compares your current and proposed contribution rates side by side, so you can see the exact change in take-home pay before you touch your payroll settings. Enter a gross pay figure, pick a new percentage, and the retirement savings trade-off becomes a number instead of a guess. Pair this with the 401k calculator for a fuller picture before you make a decision.
What the change does to each paycheck
Change in take-home per paycheck
–
457(b) deferral per paycheck at the new rate
–
Take-home cost of each extra $1 deferred
–
Take-home per paycheck now–
Take-home per paycheck at the new rate–
Income tax saved per year by the change–
Total pre-tax deferrals per year, both plans–
Your 2026 457(b) limit–
Your separate 2026 401(k) / 403(b) limit–
Most you can defer across both plans–
457(b) room left at the new rate–
Per-paycheck 457(b) deferral to max it out–
457(b) rates from 0% to 15%
Your 401(k) or 403(b) rate stays as entered; only the 457(b) rate changes. Because the two limits are separate, adding a 457(b) deferral never reduces what you can put in the other plan.
457(b) rate
457(b) per paycheck
Take-home per paycheck
Take-home given up vs no 457(b)
Tax saved per paycheck
Both plans per year
457(b) room left
Results are estimates for educational purposes and are not financial, tax or legal advice.
What the 457 Plan Contribution Effects on Your Paycheck Calculator Shows
A 457 plan is a deferred compensation retirement plan offered mainly by state and local governments and some tax-exempt employers. Every dollar you defer comes out of your check before income tax is figured, so a larger contribution rarely reduces your pay by the full amount. The calculator measures that gap: it runs your pay through both the current and the new contribution percentage and lists the result for each pay period. If you want to see how the figures change, the 401k savings with profit sharing calculator gives you an instant result you can adjust as you go.
Think of it as a payroll deduction calculator built around one decision. You are not forecasting a retirement balance here; you are checking whether a higher deferral fits inside this month's budget. Many an employee also uses it during open enrollment, when benefits elections, tax withholding changes and pre-tax contributions all get decided in the same week.
Gross Pay, Pay Period and Filing Status Inputs
Start with gross pay, the amount on one paycheck before any deductions. The calculator accepts figures from $1 to $1,000,000. Next choose how often you are paid, because the pay period sets how many checks you receive each year:
Weekly: 52 paychecks per year
Every other week: 26 paychecks per year
Twice a month: 24 paychecks per year
Monthly: 12 paychecks per year
Then select your filing status: single, married, or head of household. Choose head of household if you are unmarried with dependents, and single if you file separately from a spouse. This choice drives the standard deduction and the tax brackets used in the federal estimate.
State and Local Taxes and Pre-Tax Deductions
Enter your state and local taxes as a single percentage. The tool can only estimate this withholding, so use the rate on your latest pay stub if you have it. Add any pre-tax deductions your employer takes before income tax, such as medical premiums, because those lower the wages that income tax applies to just as a 457 deferral does.
Post-Tax Deductions and Expected Salary Change
Items taken from money that has already been taxed go in the post-tax deductions box, and after-tax reimbursements go in their own field. If you expect a raise, the salary change field projects your future contributions and any matching amount. Finally, year to date earnings tell the tool whether you have already passed the Social Security wage base for the year.
Current Balance, Current Age and Age at Retirement
Fill in your current balance, current age and age at retirement to see what the new rate could add to your plan over time. The calculator assumes no contribution in the year you retire, so if you retire at 65 your last deferral happens at 64.
How a 457(b) Calculator Turns a Deferral Percentage into Take Home Pay
A 457(b) calculator that focuses on paychecks follows the same order your payroll department uses. Your deferral percentage is applied to gross pay, then each tax is figured from the correct wage base: The 401k spend or save calculator online is free to use with no sign-up, and works on desktop and mobile.
$$\text{Take-home pay} = G - D - T_{fed} - T_{state} - T_{FICA} - P$$
Here \(G\) is gross pay, \(D = G \times \text{deferral rate}\) is the amount you defer, \(T_{fed}\) and \(T_{state}\) are income tax withheld, \(T_{FICA}\) is Social Security plus Medicare, and \(P\) is any post-tax deduction. Because income tax is calculated on \(G - D\) (less the standard deduction), the federal and state terms shrink when \(D\) grows.
Social Security Tax and Medicare Tax Still Apply
A 457 deferral does not reduce FICA. The Social Security tax is 6.2% of gross wages up to the annual wage base, and the Medicare tax is 1.45% of every dollar with no cap. Your employer pays a matching share on top of that. That is why raising your contribution never changes these two lines on your stub.
Federal Income Tax Withheld and the W-4
The federal income tax estimate follows the withholding method in IRS Publication 15, which relies on the information you gave your employer on the W-4. Claiming fewer adjustments leaves more income tax withheld from each check; claiming more leaves a bigger paycheck and, sometimes, a bill at filing time. Check that your W-4 still matches your situation before you rely on the estimate.
Additional Medicare Tax and Year to Date Income
Wages above $200,000 in a calendar year trigger an additional Medicare tax of 0.9%. If you have been paid for part of the year already, enter your year to date income so the calculator knows whether this paycheck crosses the threshold. The same entry decides if you have already finished paying Social Security tax for the year.
Worked Example: Raising a Deferral from 4% to 9% of a $2,480.00 Paycheck
Suppose you are paid every other week, file as single, have a 4.5% flat state rate, and earn $2,480.00 gross per check, or $64,480.00 a year. You contribute 4% today and want to test 9%. The inputs and results look like this:
Paycheck line
Current 4%
New 9%
Gross pay
$2,480.00
$2,480.00
457 deferral
$99.20
$223.20
Federal income tax
$201.85
$186.97
Social Security tax
$153.76
$153.76
Medicare tax
$35.96
$35.96
State income tax
$107.14
$101.56
Take-home pay
$1,882.09
$1,778.55
Where each dollar of the $2,480.00 example paycheck goes at a 9% deferral.
The deferral rises by $124.00, yet take-home pay drops by only $103.54. The difference, $20.46, is the tax savings from a smaller taxable base: $14.88 of federal tax and $5.58 of state tax. Over 26 checks, you add $3,224.00 to the plan while your yearly spending money falls by $2,692.04.
See how the 457 Plan Contribution Effects on Your Paycheck Calculator works: change the inputs and the change in take-home per paycheck updates instantly. Enter your own numbers in the calculator above.Raising the deferral by $124.00 lowers take-home pay by only $103.54.
For this example the federal estimate uses a $16,100 standard deduction and the 10%, 12% and 22% brackets, so the taxable amount is $64,480.00 − $5,803.20 − $16,100 = $42,576.80 at the new rate.
Take-home pay for other deferral and state tax combinations; the outlined cell is the worked example.
Annual Contribution Limits and Catch-Up Rules for 457 Plan Payroll Calculator Users
Every payroll calculator for these plans caps your contribution at the plan maximum, and the cap changes with inflation. For 2026 the annual contribution limits allow $24,500 of employee deferrals to a 457(b). Employer contributions generally do not count against your own limit, which is why the calculator never subtracts them.
Catch-Up Contributions for Older Workers
Workers age 50 or older can add a catch-up amount, $8,000 in 2026, and savers aged 60 through 63 may qualify for a larger $11,250 amount. Some governmental plans also let you catch up in the three years before normal retirement age. The amount is indexed to inflation in $500 increments, so check the current figure each January. In the calculator, an older saver simply raises the new percentage until the annual contribution reaches the higher ceiling, and the take-home line shows what each extra point costs per check.
Highly Compensated Employees
Some plans apply extra rules to employees classified as highly compensated, and those limits depend on how many coworkers participate. If your plan sets a lower cap for you, enter a deferral percentage at or below it, since the calculator only enforces the general limit. If you think this applies, ask your plan administrator.
Percentage Limits and Maximum Contribution
The calculator limits a deferral to 75% of pay so enough remains for FICA. Your plan may be lower. Before you commit to a new rate, compare it with the plan's maximum contribution so that your final paychecks of the year are not shorted.
Testing an 8% Deferral with the 457(b) Calculator on a Semi-Monthly Check
Marisol works for a county water department, is paid twice a month, and files jointly with her husband. Her gross is $3,187.50 per check, she contributes 3% to the county's 457(b), and her household needs $2,350.00 from each check to cover the mortgage, the car note and groceries. A raise-free way to save more is tempting, but only if the bills still clear.
She picks "twice a month," "married," a 5% state rate and enters 3% as current and 8% as new. The calculator returns two columns:
At 3%: $95.62 deferred, $189.36 federal tax, $243.84 FICA, $154.59 state tax, so $2,504.08 take-home
At 8%: $255.00 deferred, $170.23 federal tax, $243.84 FICA, $146.62 state tax, so $2,371.80 take-home
The deferral grows by $159.38, but her check shrinks by only $132.28, because $27.10 comes back as lower income tax withholding. Over 24 checks she would defer $6,120.00 for the year, about a quarter of the $24,500 limit for 2026, so the cap is not a concern.
The $2,371.80 clears her $2,350.00 floor by $21.80. Out of curiosity she reruns the form at 10% and gets $2,318.89, which is $31.11 short of the floor. That settles it: she submits 8% to payroll now and plans to add one more point when her next cost-of-living adjustment lands in January, since that increase will cover the difference without touching the household budget.
Pre-Tax vs Roth 457 Contributions and Your Retirement Savings
You may be able to choose between two plan types. A pre-tax contribution lowers your taxable income now and is taxed when you withdraw it. A Roth 457 contribution is made on an after-tax basis, so it does not shrink your paycheck's tax line, but qualifying distributions come out tax-free.
When a Pre-Tax Deferral Wins
If you expect a lower tax rate in retirement than today, the immediate reduction in withholding is hard to beat. The result in the example above, a $103.54 cost for a $124.00 deferral, shows that benefit in real numbers.
When Roth Contributions Make Sense
If you expect a higher tax bracket later, paying tax now can win. A Roth amount of $223.20 per paycheck would leave the tax lines unchanged, so take-home pay would fall by the full deferral. The calculator's plan type selector lets you compare the two.
Withdrawals, Early Access and Distributions
A governmental 457(b) has an unusual feature: money can be withdrawn after you leave your job without the 10% early withdrawal penalty, although ordinary income tax still applies. Upon reaching age 73 you must take required minimum distributions, a point the calculator's projection does not model.
Employer Match, Rate of Return and Plan Balance Growth
Beyond the take-home comparison, the calculator projects what the higher deferral could become by your retirement age. If your employer offers an employer match, those employer contributions add to your plan balance at no cost to your paycheck, though not every governmental plan has one. The projection uses these inputs:
Rate of return: the assumed yearly growth of your investments, before fees
Compound interest: growth earned on earlier growth, which is why starting the higher deferral now matters
Time horizon: the years left before you stop working
Inflation: not modelled, so read the projected balance in future dollars
The annual salary you enter matters twice: a higher yearly salary turns each percentage into a bigger dollar deferral, and the salary change input raises later contributions. Every employee faces a different investment menu and fee schedule, so treat the projected figure as an estimate. If the new rate raises your retirement savings enough to matter, a financial advisor can check the investment mix behind it, and your retirement account statement shows the real investment returns to compare against the calculator's assumption.
Other Payroll Deductions That Change Your Take Home Pay
A 457 deferral is rarely the only line between gross and net. Other payroll deductions sit around it, and some are taken before tax too:
Flexible spending account: a pre-tax account for qualified costs, usually with a use-it-or-lose-it rule
Health savings account: a pre-tax deposit that you keep with no yearly forfeiture
Health insurance: premiums often paid before tax
Life insurance: frequently a post-tax deduction
Reimbursements: after-tax payments from your employer that add to your check
Enter each in the correct box, since placing a post-tax item among the pre-tax deductions would overstate your tax savings. If a line on your stub is unclear, human resources can explain how it is treated.
457 Plan Contribution Effects on Your Paycheck Calculator questions
Does a 457 contribution reduce my Social Security and Medicare taxes?
No. Deferrals to a 457 plan lower your income tax withholding, but Social Security (6.2%) and Medicare (1.45%) are still figured on your full gross pay.
Why does my paycheck drop by less than the amount I add?
A pre-tax deferral lowers the pay your federal and state income tax is based on, so part of the extra savings comes back as smaller tax withholding. The calculator shows this as the income tax savings per paycheck.
What is the 2026 contribution limit for a 457(b) plan?
The 2026 employee deferral limit is $24,500, with catch-up amounts for savers age 50 and over. The calculator caps the annual contribution at the applicable limit.
What is the difference between pre-tax and Roth 457 contributions?
Pre-tax contributions reduce taxable pay now and are taxed when withdrawn. Roth (after-tax) contributions do not reduce your paycheck's tax withholding, but qualifying withdrawals are tax-free.
Does the calculator include my employer match?
Yes, if your plan has one. Enter the match percentage and the maximum percentage of salary your employer will match; enter 0 if your plan has no match.
What are pre-tax deductions, and should I enter them?
Pre-tax deductions, such as health insurance premiums, are taken before income tax. Enter them so the tax estimate reflects the real taxable pay on your stub.
How accurate is the federal withholding estimate?
It is an estimate based on current standard deductions and tax brackets for your filing status. Your actual withholding depends on your W-4 and your employer's payroll system.
Can I use it if I am paid weekly or monthly?
Yes. Choose weekly, every other week, twice a month or monthly in the pay period field, and enter your gross pay for that single pay period.