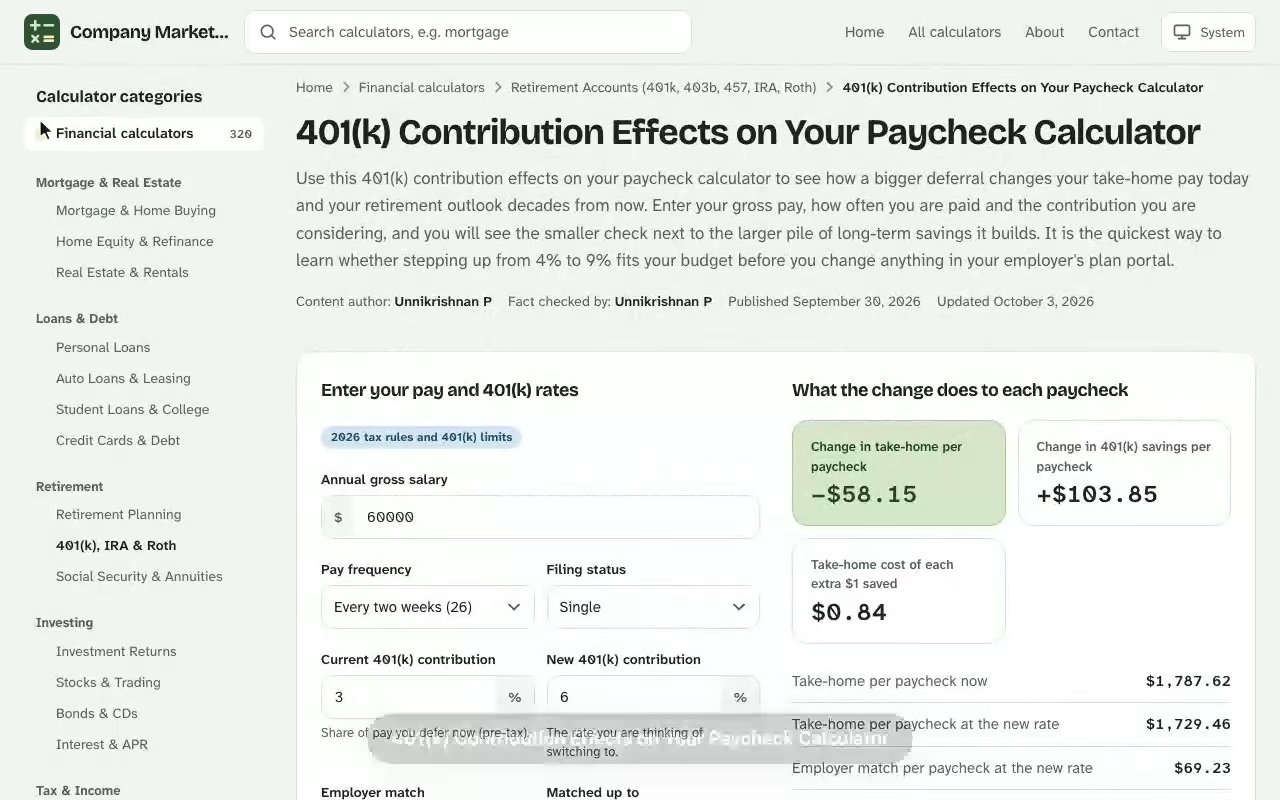
401(k) Contribution Effects on Your Paycheck Calculator
401(k) Contribution Effects on Your Paycheck Calculator. Use this 401(k) contribution effects on your paycheck calculator to see how a bigger deferral changes your take-home pay today and your retirement outlook decades from now. Enter your gross pay, how often you are paid and the contribution you are considering, and you will see the smaller check next to the larger pile of long-term savings it builds. It is the quickest way to learn whether stepping up from 4% to 9% fits your budget before you change anything in your employer's plan portal. If you want to see how the figures change, the 401k calculator gives you an instant result you can adjust as you go.
What the change does to each paycheck
Change in take-home per paycheck
–
Change in 401(k) savings per paycheck
–
Take-home cost of each extra $1 saved
–
Take-home per paycheck now–
Take-home per paycheck at the new rate–
Employer match per paycheck at the new rate–
Income tax saved per year by the change–
Employer match left unclaimed per year–
Your 2026 401(k) contribution limit–
Current vs new paycheck
Each line per paycheck. The difference column shows how each item moves your take-home pay.
Item
Current rate
New rate
Difference
Take-home pay at every rate from 0% to 15%
How each extra 1% of pay you put in your 401(k) changes your paycheck and your total savings, with your employer match included.
You contribute
Your 401(k) per paycheck
Match per paycheck
Take-home per paycheck
Take-home given up vs 0%
Total saved per paycheck
Total saved per year
Results are estimates for educational purposes and are not financial, tax or legal advice.
How a 401(k) Contribution Calculator Changes Your Paycheck
A traditional 401(k) takes your contribution out of each paycheck before income tax is figured, so every dollar you defer lowers your taxable income. That is why a 5-point jump in your contribution never shrinks your check by a full 5%: part of the contribution is paid for by pre-tax dollars that would otherwise have gone to the IRS. A 401(k) contribution calculator does that gross-to-net arithmetic for you and shows both sides of the trade, a lower check now and a larger account later. Try the free 457b catch-up calculator to run your own numbers — everything is calculated in your browser and nothing you enter is stored or sent anywhere.
Three things happen when you raise your percentage. Your retirement account receives more money each pay period, your federal withholding and state withholding fall because less of your pay is taxable, and your FICA taxes stay exactly where they were, because Social Security and Medicare are charged on the full gross amount. Understanding which of those lines move and which do not is the whole point of running the numbers.
What You Need Before Using a 401k Calculator
A 401k calculator is only as accurate as the figures you type in. Gather these details from your pay statement and your most recent Form W-4: Try the 401k savings with profit sharing calculator to run your own numbers — everything is calculated in your browser and nothing you enter is stored or sent anywhere.
Gross pay for one pay period, or your annual salary divided by the number of periods.
Your pay frequency: weekly, bi-weekly, semi-monthly or monthly.
Your current contribution percentage and the percentage you want to test.
Your filing status, the number of dependents and any additional withholding you requested.
Other pre-taxdeductions such as health insurance premiums or a flexible spending account.
The check date, which is your next pay date, because tax rates and contribution limits are updated every year.
Your employer's employer match formula, if one exists.
Gross Pay and Pay Frequency
Your gross pay is the amount before any tax or deduction. If you are an hourly worker, multiply your typical hours by your rate for one pay period. Because the calculator converts everything to a yearly figure, choosing the wrong pay frequency throws off every result, so confirm it on your pay statement.
Contribution Percentage and Pre-Tax Deductions
Enter your contribution percentage as a share of gross pay. Include other pre-tax items too, since health insurance premiums shrink the pay that income tax is figured on and change how much a 401(k) deferral really costs you.
The Paycheck Calculator Formula: Gross Pay to Net Pay
Every paycheck calculator follows the same gross-to-net logic. Your net pay is gross pay minus your 401(k) deferral, minus income tax computed on what remains, minus FICA, minus any other deduction:
See how the 401(k) Contribution Effects on Your Paycheck Calculator works: change the inputs and the change in take-home per paycheck updates instantly. Enter your own numbers in the calculator above.
$$\text{Net pay} = G - C - T_{fed} - T_{state} - F - D$$
where \(G\) is gross pay, \(C = G \times p\) is the 401(k) deferral at contribution percentage \(p\), \(T_{fed}\) and \(T_{state}\) are income-tax withholding on \((G - C - D)\), \(F = G \times 0.0765\) is FICA, and \(D\) is every other deduction. The change in your paycheck from raising the percentage is therefore:
$$\Delta\text{Net} = \Delta C \times (1 - t_{marginal})$$
Here \(t_{marginal}\) is your combined federal and state marginal rate, so a higher bracket means a cheaper deferral.
Worked Example: Federal 401k Calculator Results for a 4% to 9% Raise
Suppose your annual salary is $82,600 and you are paid bi-weekly, 26 times a year, so your gross pay is $3,176.92 per check. You contribute 4% today and want to know what 9% would do. Assume a 22% federal marginal rate and 4.5% state rate, and an employer that matches 50 cents per dollar on the first 6% of pay.
Line
At 4%
At 9%
Change
401(k) deferral per check
$127.08
$285.92
+$158.84
Federal withholding saved
-
-
$34.95
State withholding saved
-
-
$7.15
Net paycheck reduction
-
-
-$116.74
Employer match per check
$63.54
$95.31
+$31.77
Total added to the account per check
$190.62
$381.23
+$190.61
Annual total saved, including match
$4,956
$9,912
+$4,956
The five extra points move $158.84 into your account each pay period, yet your take-home check drops only $116.74, because the pre-tax treatment returns $42.10 through lower withholding. Meanwhile your employer adds another $31.77 per check, so the account grows by $190.61 for a cost of $116.74. Over 26 pay dates in a year the net cost is about $3,035 while the account gains $4,956 each year.
401(k) Contribution Effects on Your Paycheck Calculator: Reading the Results
After you click the calculate button, most tools return a bar graph or a table that places your current and proposed numbers side by side. Read it in this order: first the new take-home figure, then the amount going into the account, then the projected balance. If you invest the extra $4,956 a year at a 6% rate of return for 20 years, the end-of-year balance from the increase alone is roughly $182,300 before inflation, a projection and not a promise.
Take-Home Pay Versus Retirement Savings
The useful comparison is not the raw reduction in your check but the ratio between the two. In the example, you give up $116.74 to add $381.23 to your retirement savings in total, counting the match. That is the kind of figure to weigh against your monthly bills, your emergency fund and your retirement goals.
Why the Check Shrinks Less Than the Contribution
Income tax is withheld on what is left after the deferral. A person in a higher bracket gets back a larger share of each dollar, while a lower-bracket employee gets back less. Either way, FICA taxes are unchanged, so the check never falls by less than the 7.65% already coming out of the gross amount.
Employer Match, Annual Limit and Catch-Up Contribution
Employer Match Is Free Money
An employer match is the most valuable part of any plan. A match of 50 cents per dollar on the first 6% is a guaranteed 50% return on that slice, which is why advisers call it free money. If you contribute less than the matched percentage, you leave part of your benefits package unclaimed. The match does not change your paycheck, but it should change which percentage you pick.
The Annual Limit
The IRS caps what you may defer in a year. For 2026 the annual limit is $24,500, and workers aged 50 or older may add a catch-up contribution on top of it. A calculator that knows your check date will flag a percentage that would push you past the cap before the year ends. Employer contributions are counted separately from your own deferrals.
How Withholding and Form W-4 Shape a Paycheck Calculator Result
The size of the tax break depends on the information your employer holds. The Form W-4 tells payroll how much federal income tax to take, and the redesigned version dropped the old withholding allowances in favor of dollar-based steps for dependents and additional withholding.
Filing Status and Head of Household
Your filing status changes the width of the brackets applied to you. A taxpayer who qualifies as head of household faces wider low-rate brackets than a single filer, so the same deferral saves slightly less tax for that person. Pick the status that matches your actual return.
Pre-Tax Dollars and Tax Liability
Because deferrals reduce the wages on which tax is computed, your yearly tax liability falls too. Setting your withholding correctly also keeps you from over-paying all year and waiting on a refund. If your numbers shift, adjust the withholding on your W-4 and re-run the calculator.
Testing a 3% to 7% Step Up With a 401(k) Paycheck Calculator
Dana, a dental office manager, has just moved to a $54,750 salary paid semi-monthly, so her gross pay is $2,281.25 per check. Her employer matches 100% of the first 3%, and she has contributed exactly 3% since her first week. Before an open-enrollment deadline, she wants to know whether 7% is realistic, and she gives herself one rule: her check may not fall by more than $85.
She opens the paycheck calculator with her pay statement beside her and enters:
Gross pay: $2,281.25, pay frequency: semi-monthly (24 checks a year)
Current contribution: 3% ($68.44), planned contribution: 7% ($159.69)
Federal marginal rate: 12%, state rate: 3.07%
The tool shows the extra deferral of $91.25 per check. Of that, $13.75 comes back through lower federal and state withholding, so her take-home pay falls by $77.50 per check, or $1,860 over a year. Her annual deferral reaches $3,832.50, about 15.6% of the $24,500 IRS annual limit for 2026, so no limit is in play. The match stays at $68.44 per check because she already collected all of it at 3%; the extra four points are purely her own saving.
$77.50 sits under her $85 ceiling, so the result decides the next step: she submits 7% in the plan portal rather than the 6% she had considered as a fallback. She will rerun the calculator at 8% only after her next raise, when the check can absorb it.
Traditional or Roth: Retirement Savings Calculator Inputs That Change Your Check
The plan type you pick changes what the calculator shows on payday. A traditional 401(k) provides tax-deferred contributions and tax-deferred growth, so your check falls by less than the deferral and taxes are due on every withdrawal. A Roth option takes after-tax money instead, so your check shrinks by the full contribution, but later retirement income is untaxed. Enter the plan type before you compare results, because the same deferral produces a different result under each.
If your plan has no Roth choice, a Roth IRA or a traditional IRA is the usual alternative, and small employers that add a plan can claim a tax credit under SECURE 2.0. Neither alters your own paycheck math.
A constant deferral also works as dollar-cost averaging: the same deferral lands every pay period, so the per-check figure the calculator reports stays predictable. That steady investment is what the annual projection builds on, and it makes each raise easy to budget around. Any investment grows best when you can sustain it.
Choosing a Contribution Percentage With a 401k Calculator
Start by contributing enough to earn the full employer match.
Raise your contribution percentage by one or two points whenever you get a raise, so your take-home pay never visibly falls.
Test several percentages until you find a figure you can live with for both today's and tomorrow's needs.
Revisit the numbers at different stages of your career, since your capacity to save changes.
Check the annual limit before the year ends, especially if you are close to the cap.
Each small raise costs less than its face value because of the tax effect described above, and the calculator shows that exact cost, so a one-point step toward your nest-egg stays easy to approve. Your wages and income will change, so rerun your numbers each time they do.
Limits of Any Paycheck Estimate
Calculators give monthly and per-check estimates based on standard rules. They cannot see a bonus, a wage garnishment or a local tax. Treat the result as a planning tool, confirm exact amounts on your next pay statement, and talk to a tax professional if your situation is complicated.
401(k) Contribution Effects on Your Paycheck Calculator questions
How much will my 401(k) contribution reduce my paycheck?
Less than the contribution itself. Traditional 401(k) deferrals come out before income tax is figured, so lower federal and state withholding returns part of each dollar. Social Security and Medicare taxes are unchanged.
Does an employer match change my take-home pay?
No. The match is deposited into your account by your employer and does not reduce your check, but it is included in the projected annual savings.
Is there a limit to 401(k) contributions?
Yes. The IRS sets an annual limit on employee deferrals, with an additional catch-up amount for workers aged 50 or older. The calculator flags a yearly deferral above $24,500.
Why does my Form W-4 matter?
Your W-4 filing status, dependents amount and extra withholding determine how much federal income tax your employer holds back, and therefore how much a deferral saves in tax.
Can I put 100% of my paycheck into my 401(k)?
Plans set their own maximum percentage, and the IRS annual limit applies regardless. Your remaining pay must also cover taxes and other deductions.
What is the difference between a traditional and a Roth 401(k) for my paycheck?
A traditional deferral lowers your taxable pay, so your check falls by less than the contribution. A Roth contribution is made after tax, so your check falls by the full amount.
How accurate is this paycheck estimate?
It is an estimate using the federal annualized method with a flat state rate. Bonuses, local taxes and employer-specific rules can change your actual check, so confirm on your pay statement.